DOL won’t crack down on financial advisers who engage in prohibited transactions
The temporary ban will remain in place until the SEC posts its final fiduciary rules.
Follow Us
© 2026 Arizent. All rights reserved.

The temporary ban will remain in place until the SEC posts its final fiduciary rules.
With the rescue attempt's failure, all eyes now turn to the SEC which is considering its own proposal for raising financial advisor standards of conduct.
The regulator's proposal is set to remake compliance standards for brokers and advisors.
With a recent uptick in 401(k) related lawsuits, employers should take concrete steps to help participants while giving their company the fullest extent of protection possible against potential litigation.
The regulator's proposal is set to remake compliance standards for brokers and advisors.
With a recent uptick in 401(k) related lawsuits, employers should take concrete steps to help participants while giving their company the fullest extent of protection possible against potential litigation.
Whether the broker acts as a fiduciary making a recommendation will depend upon the circumstances of the particular recommendation and their client.
New rules would set standards of conduct for brokers, require new disclosures and offer interpretive guidance for fiduciary advisors.
New rules recognize the fact that commission-based transaction services can be the most cost effective way for Main Street investors to receive financial advice.

Despite the recent Fifth Court ruling, it’s too soon to say the regulation is dead. There may be a rehearing, and most importantly, best practice standards will live on.
Despite the recent Fifth Court ruling, it’s too soon to say the regulation is dead. There may be a rehearing, and most importantly, best practice standards will live on.
Focus turns to the SEC as it considers creating its own higher standard of client care.
Plan sponsors should keep in mind that while the coverage isn’t legally required, it’s needed protection if breach accusations occur.
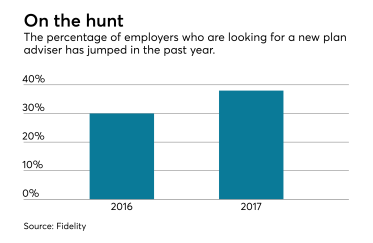
Employers are looking for a partner who is knowledgeable about regulatory changes, will focus on improving 401(k) performance and will help minimize costs.
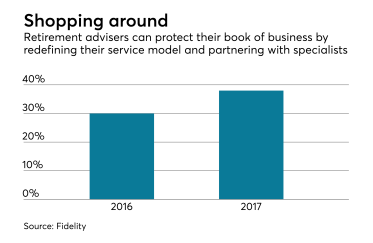
Retirement advisers can protect their book of business by redefining their service model and partnering with specialists.
Financial advisors can still be held liable for violating impartial conduct standards even though the fiduciary rule has been delayed until 2019.

The regulation's enforcement provisions will not take effect until July 1, 2019, the Labor Department said.
Saving too much for retirement could force clients to take loans or make withdrawals that would carry taxes and penalties.
Saving too much for retirement could force clients to take loans or make withdrawals that would carry taxes and penalties.
Moving funds into an advised account constitutes fiduciary investment advice and must be monitored carefully.