8 tough questions to ask your 401(k) investment adviser
Plan sponsors should inquire about their adviser’s compensation, professional credentials and educational background, says retirement expert Robert Lawton.
Follow Us
© 2026 Arizent. All rights reserved.

Plan sponsors should inquire about their adviser’s compensation, professional credentials and educational background, says retirement expert Robert Lawton.
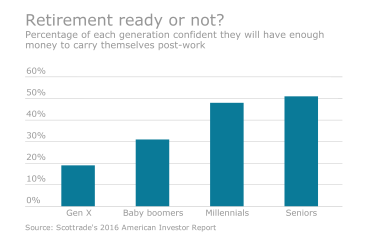
Plan sponsors should connect with workers by integrating financial wellness concepts, including behavioral finance/economics elements, talking about loans and withdrawals and offering one-on-one meetings.
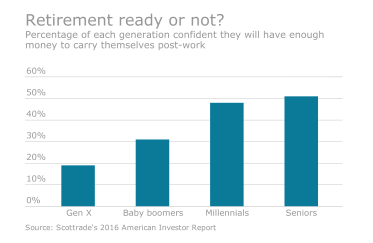
Plan sponsors should connect with workers by integrating financial wellness concepts, including behavioral finance/economics elements, talking about loans and withdrawals and offering one-on-one meetings.
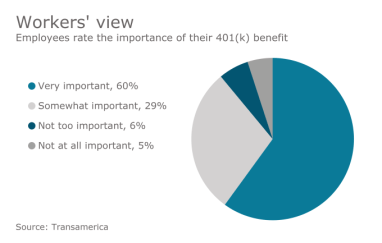
Employers should auto-enroll employees, offer health savings accounts and provide financial education online.
Plan sponsors should limit the number of fund selections, provide more fixed income choices and offer index options.
Auto-enrollment, auto-escalation, participant investment advice and Roth 401(k) availability are among the important traits of a plan.
More employers will stretch matching contributions, include HSA information in education sessions and incorporate behavioral economics/finance elements in plan design.
Plan sponsors should document meetings, put employee needs first and ensure they have a properly structured retirement plan committee.
Using lowest-cost share classes, performing an annual investment fund review and distributing required fee notices are among best practices.
More companies will stretch matching contributions, include HSA information in education sessions and incorporate behavioral economics/finance elements in plan design.
Using lowest-cost share classes, performing an annual investment fund review and distributing required fee notices are among best practices.
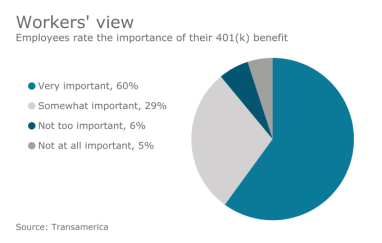
More employers will stretch matching contributions, include HSA information in education sessions and incorporate behavioral economics/finance elements in plan design.
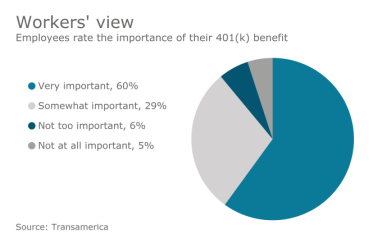
Plans sponsors can remove many of the barriers that prevent employees from taking full advantage of 401(k)s.
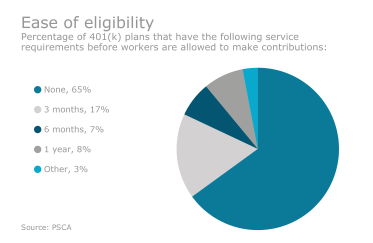
Plan participants should review a full market cycle, index efficient asset classes and eliminate closet indexers.
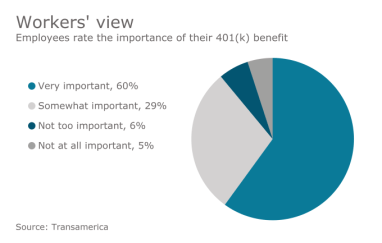
Employers should give employees a risk assessment quiz every year, offer free and basic investment advice and adopt an auto-enrollment provision.
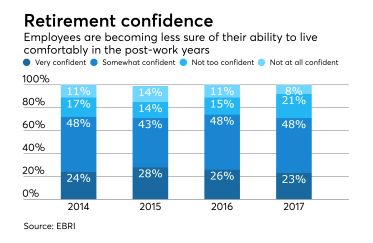
The retirement plan gives employees freedom to direct investments and to accumulate savings.
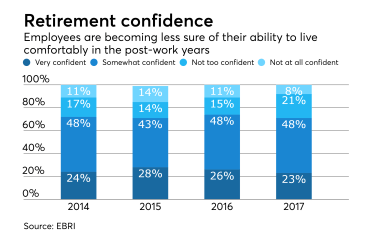
The retirement plan gives employees freedom to direct investments and to accumulate savings.
Retirement readiness would vastly improve by requiring auto features, increasing HSA contribution limits, and outlawing participant loans, among other recommendations, says adviser Robert Lawton.
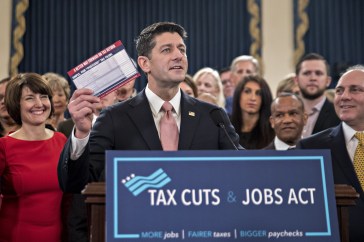
By leaving retirement accounts as is, Congress missed an opportunity to help workers who have not saved for the future.
Retirement readiness would vastly improve by requiring auto features, increasing HSA contribution limits, and outlawing participant loans, among other recommendations, says adviser Robert Lawton.