Benefits Think 10 key features of a retirement-ready 401(k)
Auto-enrollment, auto-escalation, participant investment advice and Roth 401(k) availability are among the important traits of a plan.
Follow Us
© 2026 Arizent. All rights reserved.

Auto-enrollment, auto-escalation, participant investment advice and Roth 401(k) availability are among the important traits of a plan.
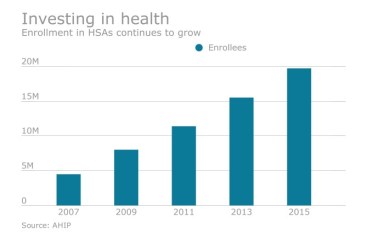
In addition to being triple tax-free, health savings accounts can make a significant difference for workers’ retirement planning.
Plan sponsors should follow a four-step process to ensure their providers are appropriate and that the fees paid are reasonable, says adviser Robert Lawton.
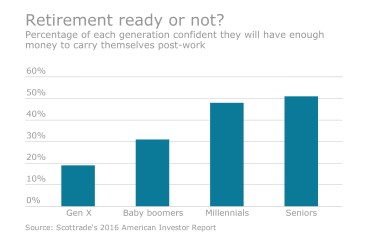
Staying in a plan’s qualified default investment alternative rebalances employee accounts and ensures age-appropriate allocations.
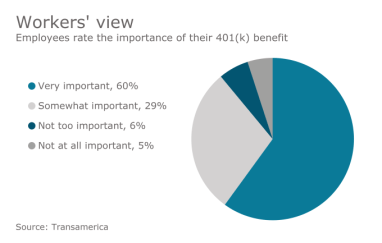
When making retirement updates, plan sponsors should consider fees, features and fiduciaries.
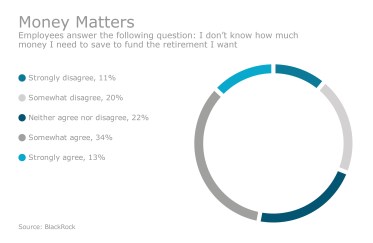
Guidance is sound if it’s coming from a fiduciary, fits the corporate culture and is comprehensive.
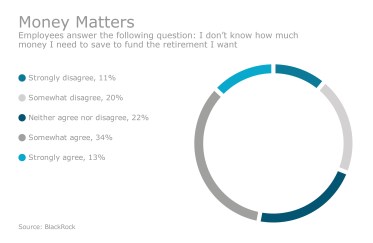
Employees have some simple but significant false ideas about their retirement plans. And employers need to do a better job addressing them during education sessions.
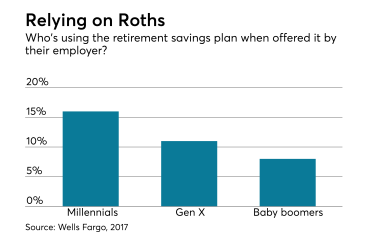
Employees will have more money in retirement if they contribute to the right savings account.
An IPS is a key part of the fiduciary compliance process and should clearly state roles and responsibilities.
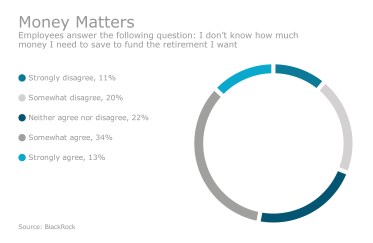
The best retirement providers should sign on to a plan as a fiduciary, provide a complete menu of services and have a clean background.
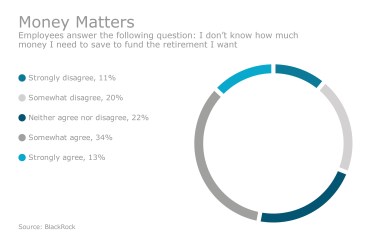
The best retirement providers should sign on to a plan as a fiduciary, provide a complete menu of services and have a clean background.
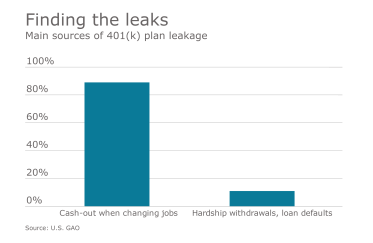
Plan sponsors should limit loans to hardship criteria, allow just one at a time and refer potential borrowers to an employee assistance program for financial counseling.
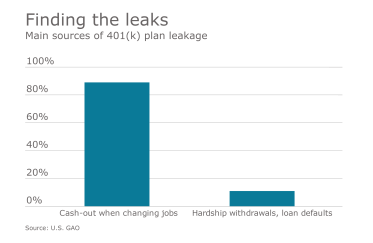
Plan sponsors should limit loans to hardship criteria, allow just one at a time and refer potential borrowers to an employee assistance program for financial counseling.
Renaming options using the asset class name they represent lacks transparency, causes participant frustration and is not a best practice.
Borrowers often end up stopping their retirement plan contributions while they are paying back their advances.
Borrowers often end up stopping their retirement plan contributions while they are paying back their advances.
Participants appear to experience dues on the principal portion that is more than double his or her incremental tax rate.
Participants appear to experience dues on the principal portion that is more than double his or her incremental tax rate.
Less volatility, lower litigation risk and greater simplicity are reasons for embracing this strategy, says adviser Robert Lawton.
Less volatility, lower litigation risk and greater simplicity are reasons for embracing this strategy, says adviser Robert Lawton.