Bill targets $10M+ retirement accounts with new distribution rules
Some ultrahigh net worth clients would be affected by a change to retirement plan contribution and distribution rules that's under consideration in Congress.
Follow Us
© 2026 Arizent. All rights reserved.

Some ultrahigh net worth clients would be affected by a change to retirement plan contribution and distribution rules that's under consideration in Congress.
The industry asked for and received a delay in the rule from the IRS in 2023. Now that it's going into effect, here are the key implications for sponsors and savers.
The spike in the number of older employees in the workplace reflects a trend over the past decade.
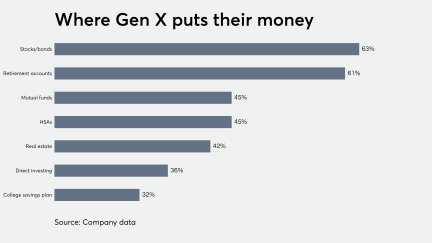
While retirement readiness among Americans has improved in general, Gen Xers are struggling with housing, college and medical costs, a survey finds.
Contributing to these accounts makes sense for clients who anticipate higher tax rates in the future.
Seniors who negotiate for such an arrangement should consider their finances, flexibility and mutual benefits.
Withdrawals for non-medical expenses would no longer be penalty-free under the proposal.
With steep competition for talent, it’s important clients think outside the conventional benefits packages to help their workforce build retirement savings.
With steep competition for talent, it’s important to think outside the conventional benefits packages to help your workforce build retirement savings.
An average couple aged 65 who are about to retire this year will need $285,000 to cover healthcare expenses.

As much as 46% believe Medicare will cover the costs of long-term care.
How state mandated employer-provided retirement plans may pave the path for a national model.
Want to have a fulfilling retirement? Employees are advised to set goals and have a bucket list of activities that will make them productive.

Premiums appear to be stabilizing finally and even dropping in some states.
Even though the program was created by a large multinational corporation, companies of all sizes could utilize this approach.
Seniors are likely to be in a lower tax bracket in the few years after retirement, creating a "sweet spot" for them to convert some of their traditional 401(k) or traditional IRA assets into a Roth account.

Socking away all retirement savings in traditional 401(k) and IRA accounts may no longer be wise.
The real question is what effect Trump’s escalating trade war will have on profits for the rest of the year.
If retirees intend to rely heavily on Social Security for income, they should consider adjusting the timing of their bills to the date that they will receive their benefits.
The differences generally come down to investor eligibility and when taxes are paid, but that can have a significant impact.
