Serving up one financial perk: early access to pay
Why one restaurant chain says giving workers advanced access to their earnings raises morale and increases productivity.
Follow Us
© 2026 Arizent. All rights reserved.

Why one restaurant chain says giving workers advanced access to their earnings raises morale and increases productivity.
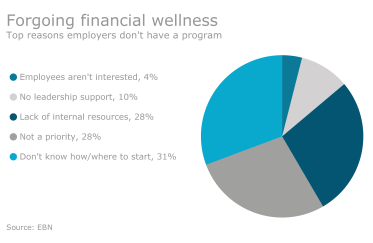
Employees who say they are not financially fit may be more prone to making poor retirement planning choices. But employers have the opportunity to step in and make a difference, experts say.
Benefit advisers have a definite role in helping employers take steps toward building a more financially-secure workforce.
Fiscal literacy isn’t taught in high school and colleges, so employers must counsel their younger workers about saving money.
Starting small, with financial checklists and cash flow worksheets, can have a large impact on plan participants.
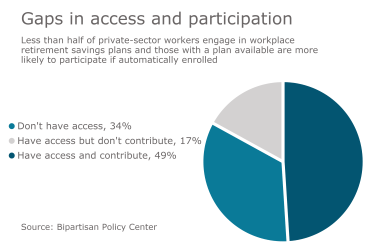
Employees who have access to a workplace plan and start saving early are in the best position to retire when they finally reach the age of 65, says the EBRI.
Insurance brokerage Willis Towers Watson’s new program aims to help workers choose the right insurance once they retire.
The latest proposal clarifies an RIA’s duty of care and other fiduciary obligations when dealing with clients.
A new benefit program at Abbott means employees won’t have to choose between paying down student debt and saving for the future.
EBRI finds that employees with access to a workplace plan and start saving early on are in the best position when they finally reach the age of 65.
Insurance brokerage Willis Towers Watson’s new program aims to help workers choose the right insurance once they retire.
Even high-net-worth clients are reluctant to discuss LTC planning, a new survey finds.
They need documentation showing how they reviewed, selected and monitor their TDFs and if their investment strategy fits with participant demographics.
Those who can't downsize can still rent out a portion of their property to help cover expenses.
Brokers are in a legal quandary: Many of them will still be fiduciaries under the 1975 Rule, but the third-party compensation they received will no longer be permitted.
When the Dow soars and dives, advisers need to reassure clients that their employees’ retirement nest egg is safe.
Advisers must develop relationships with business owners to establish customized plans that work best for the needs of their employees.
They need documentation showing how they reviewed, selected and monitor their TDFs and if their investment strategy fits with participant demographics.
Only 39% of American workers are satisfied with what their job offers and 61% are willing to take a cut in salary for a better package.