Gen Z investors are all-in on Roth. Here’s why
Generation Z is favoring Roth accounts like no generation before, new Fidelity research shows.
Follow Us
© 2026 Arizent. All rights reserved.

Generation Z is favoring Roth accounts like no generation before, new Fidelity research shows.
SIMPLE IRAs provide greater investment flexibility than traditional options, making them appealing to employers and employees alike.
In unique circumstances, contribution limits to a Roth IRA do not apply. Here’s why.
To protect client nest eggs, advisors must know which savings vehicles are protected — and they’re not all created equal.
Early withdrawals from retirement accounts may be unavoidable in today’s economic climate. You can help mitigate the damage.
For one, clients will owe taxes still on the distributions, unless they recontribute the money into the account within three years.
By extending their working years, seniors can see an increase in their Social Security payouts.
While some retirees have seen a substantial increase in spending, many others are enjoying financial freedom.
More than a quarter of women in a recent survey say they are confident they will comfortably retire, while almost a third of men voiced the same confidence.
“The advice I give is to calculate the financial impact for each option,” an expert says.
Seniors choosing between traditional and Roth IRAs must account for their current and future tax rates.
The spike in the number of older employees in the workplace reflects a trend over the past decade.
Pre-retirees may consider funding a Roth account to take advantage of tax-free compounding and tax-exempt withdrawals in retirement, an expert writes.
Nearly 48% of younger Americans feel they are not saving enough to secure their lifestyles after leaving the workforce, a report finds.
To reduce the risk of retiring early, seniors are advised to take on a part-time job or downsize to reduce expenses.
Many pre-retirees leave the workforce sooner than anticipated as a result of various factors, such as job loss and illness.
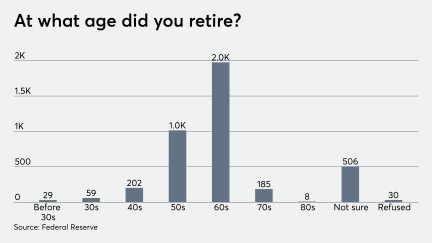
“The advice I give is to calculate the financial impact for each option,” an expert says.
This rise of the so-called grey divorce has created a number of uncommon and complex issues for retirement accounts.
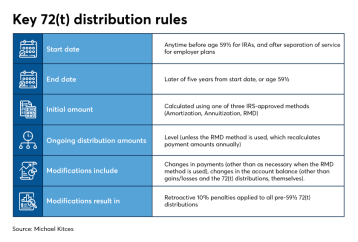
Ill-prepared investors are advised to vigorously plan their expenses and aggressively save in their 401(k)s and IRAs.
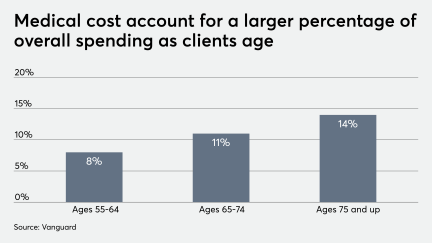
Contributing to these accounts makes sense for clients who anticipate higher tax rates in the future.