Do employees have to sign up for Medicare at 65?
There can be substantial penalties for those who are late to sign up, but when exactly is that deadline?

Follow Us
© 2026 Arizent. All rights reserved.

There can be substantial penalties for those who are late to sign up, but when exactly is that deadline?
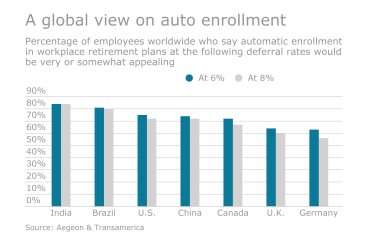
A reluctance to auto-enroll employees is one reason, but there are others for companies to consider.
By taking these into account, employers can do a better job helping employees prepare for their golden years.
GAO requests that the IRS clarify how taxpayers report their participation to gain understanding of plans that could lead to exemption.
Contributing $300 a month to a 401(k) over 40 years with an average 7% return will result in more than $700,000. So the benefits are there, but do your employees know the details?

A reluctance to auto-enroll employees is one reason, but there are others for advisers to consider.
A number of large employers are responding to the troubling trend by offering financial wellness and education programs to employees.

Making plans transferable from employer to employer can help clients attract and retain top talent.
Employees should look into filing for Social Security as soon as they retire to generate extra income and allow their spouse to delay and grow their retirement benefit.

Updated calculators and a leaner interface are intended to raise awareness of “retirement readiness.”
Regardless of the regulation’s future, employers need to ensure they’re passing costs on to plan participants that are reasonable in light of the services provided.
Regardless of the regulation’s future, employers need to ensure they’re passing costs on to plan participants that are reasonable in light of the services provided.
By taking these into account, advisers can do a better job of helping employees prepare for their golden years.
Employees are likely to miss their retirement targets if they are helping their children and loved ones more than what they can afford.
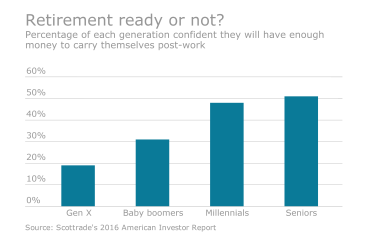
GAO requests that the IRS clarify how taxpayers report their participation to gain understanding of plans that could lead to exemption.
If plan sponsors don’t use technology to create seamless plan-to-plan portability, they risk turning their accounts into islands cut off from other retirement plans.
Robo-advisers were built on the promise of offering wealth management expertise to the masses. Now they're turning their attention to a different — and much wealthier — customer.

Workers aged 35 have to set aside 11.69% of their pay to keep up with those in their 20s socking away only 6% of their salary.
The massive shortfalls in public pension funds are the single biggest financial challenge for American’s states and cities.
Updated calculators and a leaner interface are intended to raise awareness of “retirement readiness.”