Benefits Think 5 ways to keep a retirement plan running smoothly throughout the year
Employers should build an education program, perform an objective review of investments and benchmark features.
From workplace sexual harassment to an ever-changing regulatory landscape, employers should remain vigilant and compliant in the coming year.
The beauty conglomerate added the perk to better serve its millennial-oriented workforce.
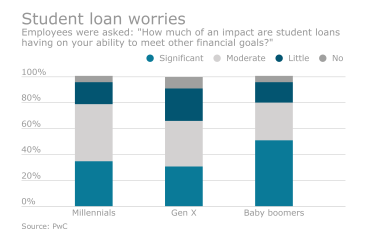
Millennials don’t know how to manage stock market expectations, Gen X struggles with savings and baby boomers don’t realize the benefits they could gain from one or two extra years in the workforce.
Retirees who consider taking withdrawals from their 401(k) and other similar plans should account for the tax impact before making a decision.
Plan sponsors worry record keepers will follow suit, limiting the investment options employers are able to offer employees through their workplace 401(k) plans.
Savers are starting to take money out of their 401(k) accounts—despite taxes and penalties involved—assuming it will be replaced as markets continue to surge upward.
Plan sponsors should end automatic cash-outs, offer roll-ins as part of a financial wellness program and engage all participants on crucial decision-making.
Cost and lack of understanding are the top reasons employers don’t provide perks to their workers.
Plan sponsors worry record keepers will follow suit, limiting the investment options employers are able to offer employees through their workplace 401(k) plans.
Retirees living overseas can still claim Social Security benefits, but they must see if their country of residence requires them to have a local bank account.
Collective Investment Trusts can have cost-saving advantages, are increasingly accessible and provide a long-term investment perspective.
More companies will stretch matching contributions, include HSA information in education sessions and incorporate behavioral economics/finance elements in plan design.
Lawmakers in Illinois are so desperate to shore up the state’s massively underfunded retirement system that they’re willing to entertain an eye-popping wager.
The Washington bank chain increased its retirement contribution to 8% following the tax reform bill.
About half of mid-sized and large companies plan to expand personal financial planning and increase retirement funds, according to a new Willis Towers Watson report.
Employees should consider that state laws may differ on who may be legally recognized as a beneficiary's spouse and thus whether their partner would be entitled to spousal benefits.
Build an education program, perform an objective review of investments and benchmark features are a few of the activities advisers should encourage now.
Using lowest-cost share classes, performing an annual investment fund review and distributing required fee notices are among best practices.
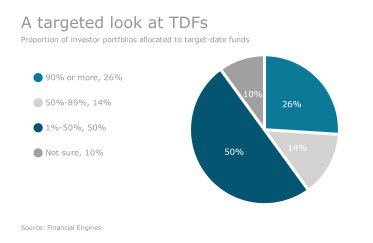
While the funds are ideal for certain people, they don't address important retirement considerations, such as the cost of funding a comfortable living and a person’s savings rate.