Plan sponsors changed retirement plans in anticipation of fiduciary rule
The regulation enacted in June spurred plan sponsors to update their plan design and investment menus and some are even shopping for new plan advisers.
Follow Us
© 2026 Arizent. All rights reserved.

The regulation enacted in June spurred plan sponsors to update their plan design and investment menus and some are even shopping for new plan advisers.
The Office of Management and Budget concluded its review of the proposal, a key step in the administrative process, which puts a freeze on further implementing the regulation.
These two accounts are both funded with money that has already been taxed, but there are still important differences that clients need to know.
A U.S. District Court has ruled that Edison International failed in its fiduciary duty by including high-fee retail share mutual funds in its 401(k) plan when lower-fee institutional ones were available.
The Trump administration is moving to further delay part of an Obama-era rule to require brokers who offer retirement advice to put their customers’ interests ahead of their own.

Make sure workers understand that a 401(k) rollover could trigger a hefty tax bill, and that liquidating assets before the age of 59 1/2 could mean a hefty penalty.
Make sure clients understand that a 401(k) rollover could trigger a hefty tax bill, and that liquidating assets before the age of 59 1/2 could mean a hefty penalty.
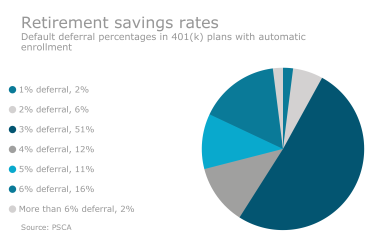
Despite uncertainty over reform efforts in Washington, employers need to prepare for next year now.
A bill repealing rule moves on to House floor, while appropriators seek to block funding for the measure.
Retirees who retire before 65 and want to reduce their premiums are advised to keep their taxable income between $12,060 and $48,240 (for singles) or $16,240 and $64,960 (married couples).
People underestimate the involvement of human professionals in digital investment services, says Betterment’s Seth Rosenbloom.

An alternative is a hybrid long-term-care policy with features of traditional LTC insurance and cash-value life coverage that grows over time.
A substantial watering-down of the protections in the rule is possible, says Carol Buckmann, so the ultimate status of the new regulation is still in question.
With the regulation now in effect, there are a number of things plan sponsors should do, including knowing if their adviser is a fiduciary or has conflicts of interest.

With the regulation now in effect, there are a number of things plan sponsors should do, including knowing if their adviser is a fiduciary or has conflicts of interest.

Fiduciary obligations are making access to up-to-date information and analytics from recordkeepers and service providers increasingly important.

A substantial watering-down of the protections in the rule is possible, says Carol Buckmann, so the ultimate status of the new regulation is still in question.
Plan sponsors need to understand how the regulation affects their roles and communication efforts — and should pay attention to exemptions.
Retirement specialists are likely to increasingly turn to recordkeepers to provide data that justifies adviser fees through strong plan performance.
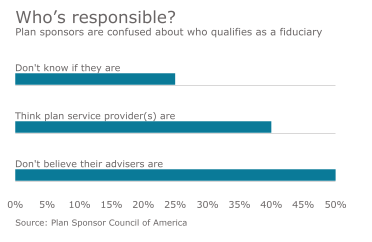
Keep in mind that there is no fee structure free of conflict, cheaper doesn’t mean better and recommendations don’t come in a vacuum, says investment strategist Jess DeGabriele.