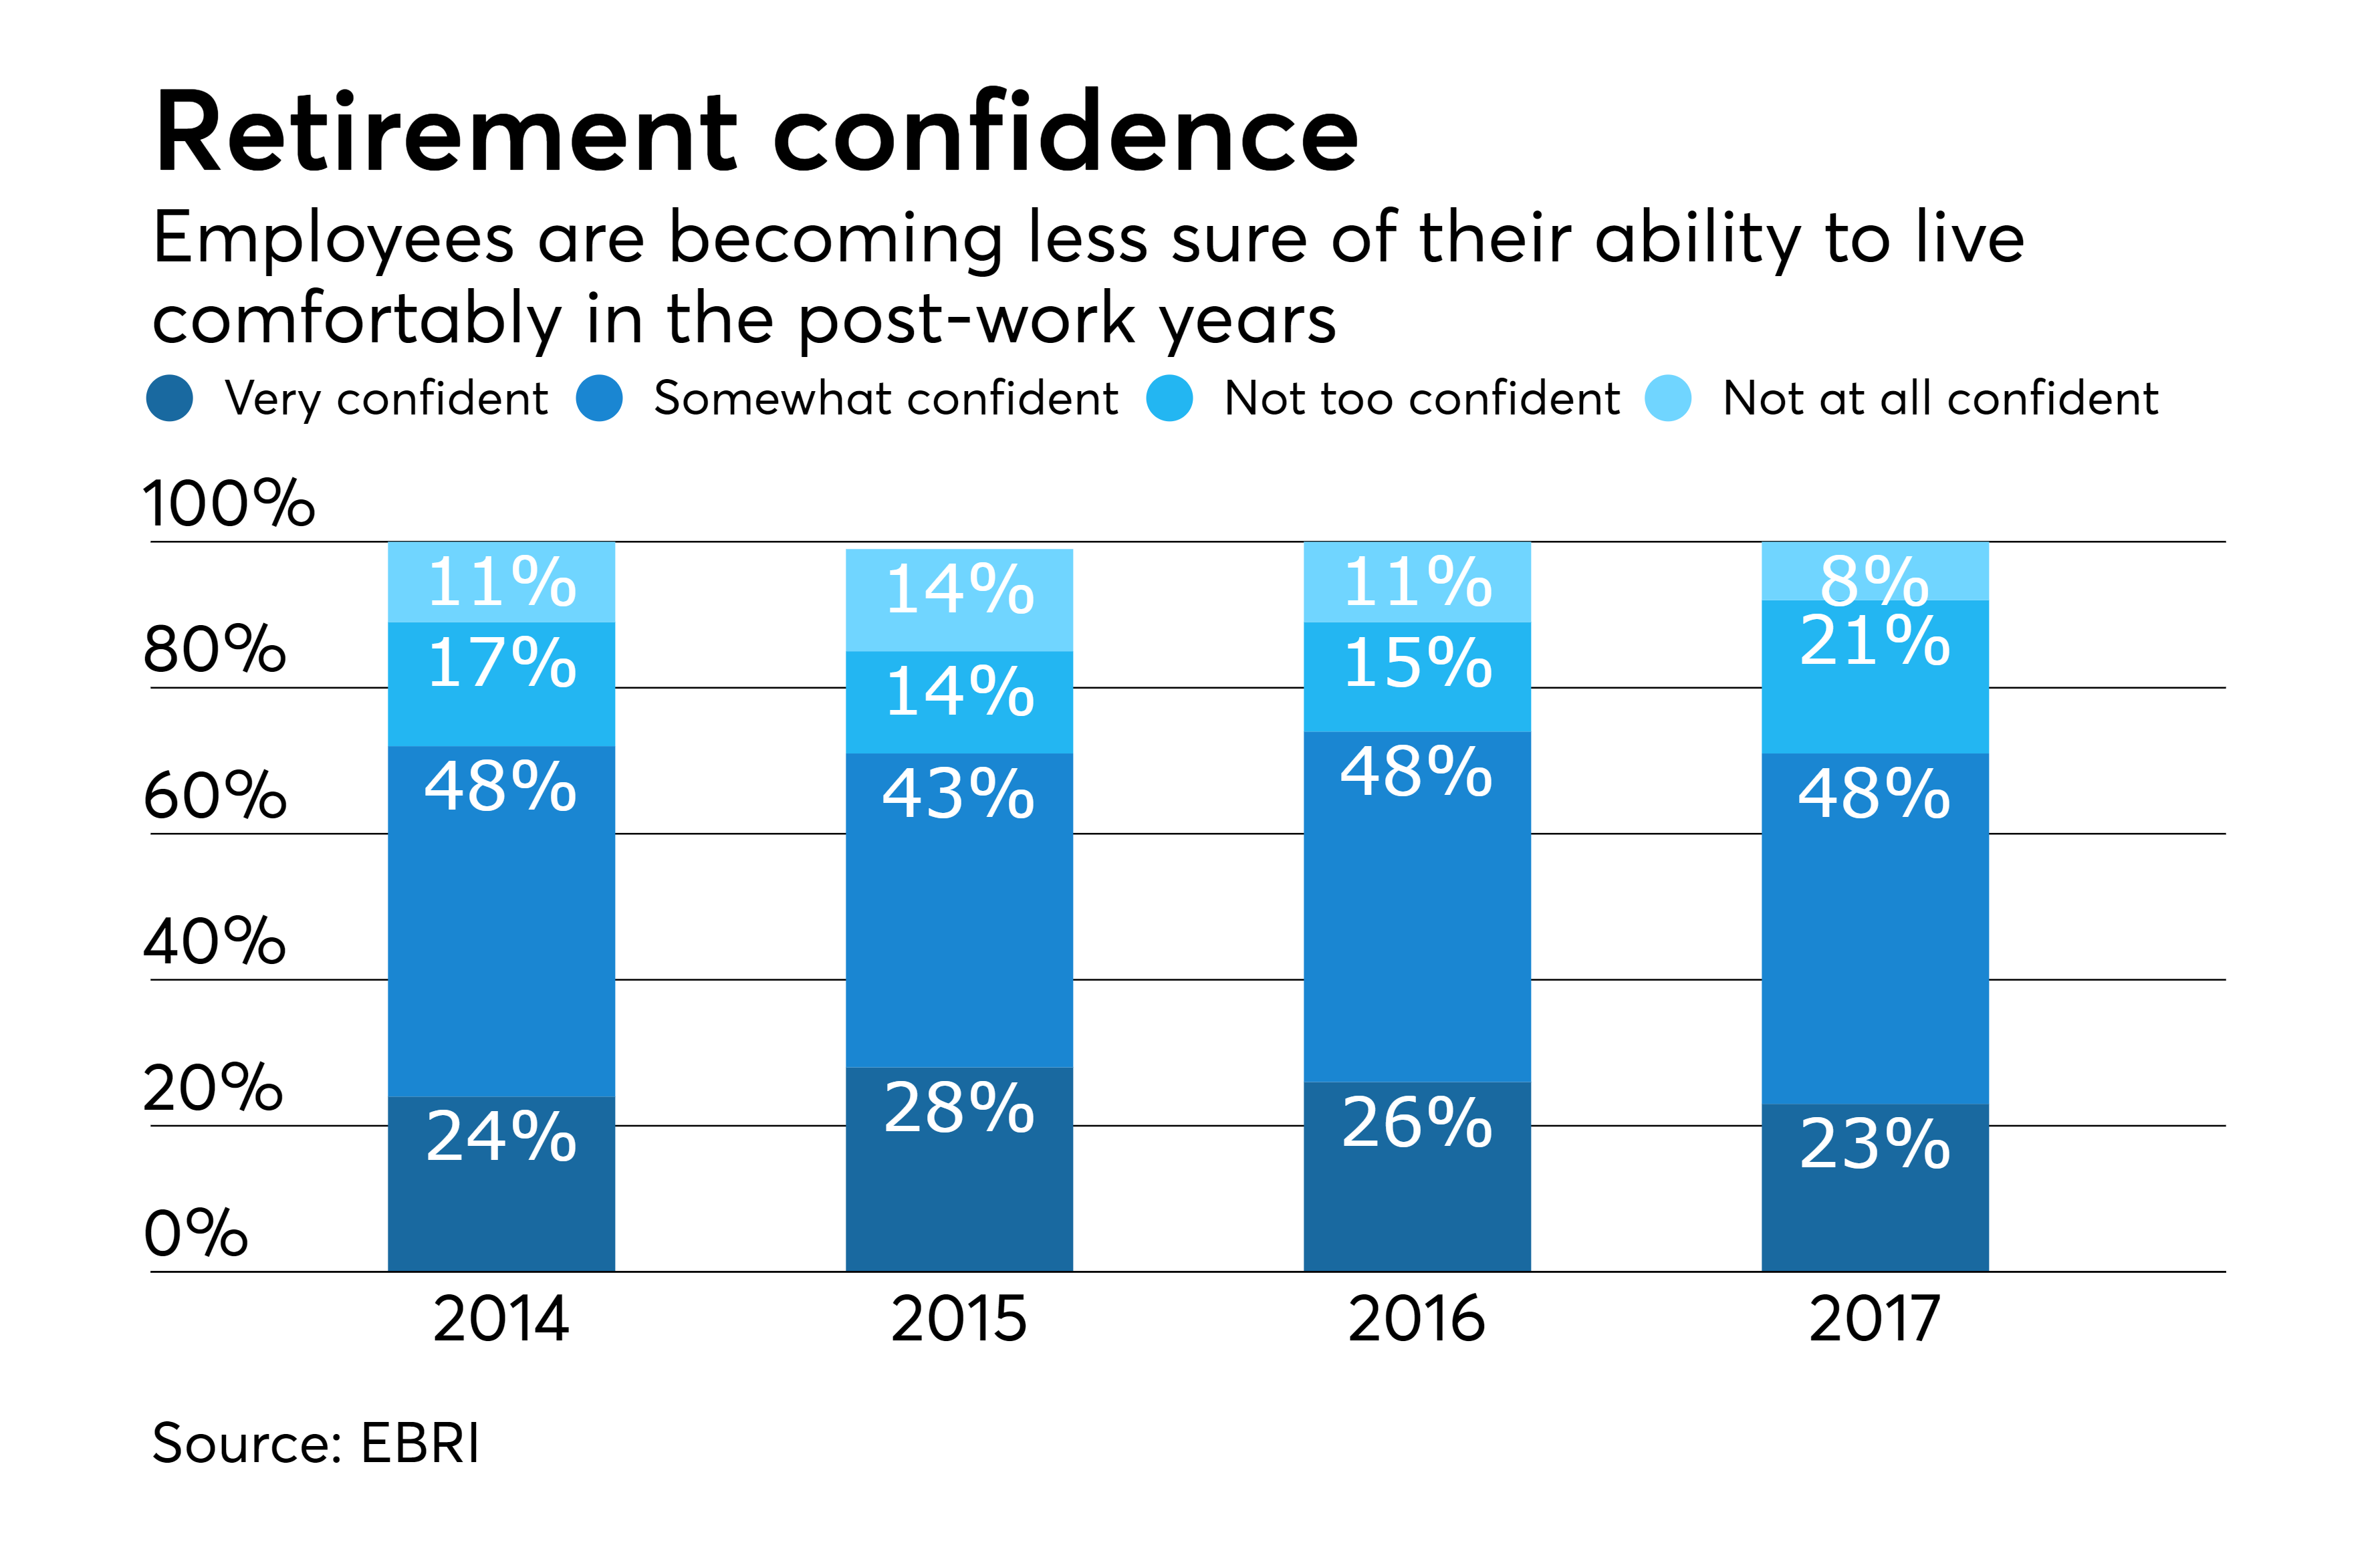
It’s bad enough that more than 50 million Americans have filed claims for unemployment benefits since the start of the COVID-19 pandemic and lockdown. But in addition to the disruption, financial hardship, and uncertainty that unemployed Americans (and their families) are experiencing right now, this crisis also threatens their financial security during retirement.
As I have written many times before in this column, defined contribution plan participants will seriously diminish their retirement savings if they prematurely cash out all or part of their 401(k) savings account balances. According to our research, a hypothetical 30-year-old who cashes out a 401(k) account with $5,000 today would forfeit up to $52,000 in earnings they would have accrued by age 65, if we assume the account would have grown by 7% per year. In addition, the Employee Benefit Research Institute (EBRI) estimates that the average American worker will change employers 9.9 times over a 45-year period. With at least 33% and as many as 47% of plan participants cashing out their retirement savings following a job change, according to the Savings Preservation Working Group, that means workers switching jobs could cash out as many as four times over a working career, devastating their ability to fund a secure retirement.