Social Security checks lower than many workers expect
Many employees expect to collect more than they actually will, which can prompt them to retire and file for benefits early and, in turn, reduce their actual payouts.
Follow Us
© 2026 Arizent. All rights reserved.

Many employees expect to collect more than they actually will, which can prompt them to retire and file for benefits early and, in turn, reduce their actual payouts.
Instead of amassing $1 million in savings, clients should consider asking themselves if they are prepared financially for several decades of retirement.
Many retirees kept their financial assets for at least 20 years after retiring, according to a study by the Employee Benefit Research Institute.
Employees have to change their retirement goals and strategies over the years, starting off heavily in stock allocation while in their 30s.
Employees who think they have lost their retirement assets are advised to seek help from the DOL or nonprofit pension counseling centers funded by HHS.
Even if an employee does not use the triple-tax-advantage of these accounts, the benefits are still valuable.
Employees should account for the tax ramifications before making such a decision.

Contributing $300 a month to a 401(k) over 40 years with an average 7% return will result in more than $700,000. So the benefits are there, but do your employees know the details?

People looking to retire but wanting to keep a part-time gig will benefit from a new law that gives a 20% deduction for “pass-through entities.”
Employees should look into filing for Social Security as soon as they retire to generate extra income and allow their spouse to delay and grow their retirement benefit.

Many employees may not be able to have a comfortable life in their golden years because they carry a hefty credit card debt into retirement
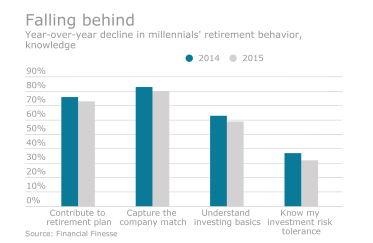
A study has found that while millennial employees are saving for retirement, they are making mistakes that can be easily corrected.
Workers aged 35 have to set aside 11.69% of their pay to keep up with those in their 20s socking away only 6% of their salary.
The bill aims to help workers think in terms of lifetime income — as opposed to accumulated balances — by requiring benefit statements to include income estimates at least once a year.
These funds can help workers put saving plans on autopilot, but they can also take on more risk than expected.

Parents should ensure that their child has earned an income adequate enough to be able to open an account, among other requirements.
In a bull market's later stages, some types of investments work better than others. Find out which ones they are.
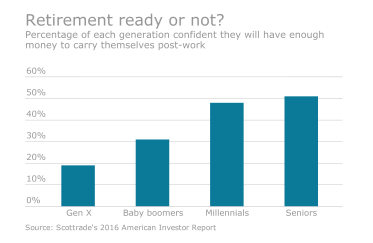
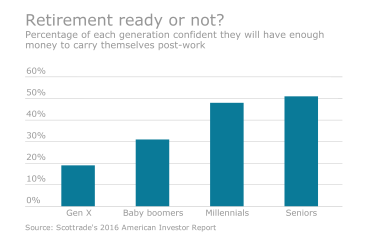
Many Gen Xers do not have enough retirement savings even as they approach their peak earning years.
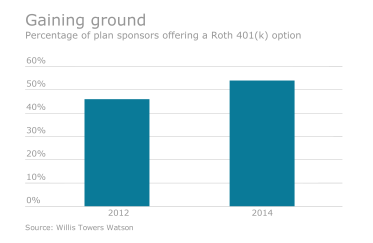
Employees who converted traditional IRA assets into Roth last year can still undo the conversion this year if they are going to pay more in taxes than what they were supposed to gain
Benefit are usually expected to replace about 40% of their pre-retirement income, but that's an average, so many workers will get even less. The question is: how much less?