Working longer may not be the solution to the retirement crisis
Age discrimination, unpredictable life shocks and involuntary retirement casts serious doubt on the “work longer” thesis.
Follow Us
© 2026 Arizent. All rights reserved.

Age discrimination, unpredictable life shocks and involuntary retirement casts serious doubt on the “work longer” thesis.
Clients adding investments other than target-date funds to their 401(k) or 403(b) could potentially hurt their bottom line.
“The big issue here is being able to maintain your standard of living,” an expert says.
The next generation can assist loved ones with applying for financial assistance, reducing expenses and developing a financial plan.
These employees will need bigger savings than other age groups to fund a longer retirement horizon, according to a study.
Before saving for retirement, young employees are advised to pay down high-interest debts and build an emergency fund, an expert says.
Employees have to increase their risk exposure to ensure they don’t outlive their savings.
Those with 1099 income have several tax-advantaged options.
The property should allow them to live close to their loved ones and fit their financial plan, according to a CFP.
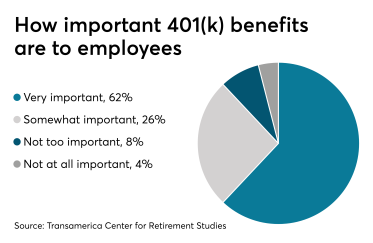
Careful planning can help prevent workers from shrinking their benefits based on misperceptions.
Target-date funds can help risk-averse young workers ease into investing.

Dual-income couples benefit less from Social Security.
Savers can expect investment returns through compounded growth as long as they don’t lose from a market downturn.
The legislation includes a provision that would raise the age limit for making contributions and taking required minimum distributions.

Plan participants should consider boosting their contribution rates if they are planning for an early retirement, says one expert.

Workers should develop a sustainable withdrawal strategy to ensure that they won't outlive their savings.

As much as 46% believe Medicare will cover the costs of long-term care.
Seniors in this position may face a tax bill and possibly a penalty if they dip into their 401(k) prematurely, says an expert.
A market correction only becomes a real risk if investors act and make buy or sell decisions to alleviate mental anguish today at the expense of tomorrow, says an expert.

A 67-year-old wife collecting spousal benefits will be better off waiting until 70 before shifting to her own retirement benefit if she remains healthy, according to this Q&A article.