Will Schwab-TD Ameritrade deal crush wealthtech innovation?
“There definitely will be people who don’t win in this,” says Altruist founder Jason Wenk.
By
Ann Marsh
Follow Us
© 2026 Arizent. All rights reserved.

“There definitely will be people who don’t win in this,” says Altruist founder Jason Wenk.
Help your employees take full advantage of the investment savings and healthcare spending benefits of HSAs.
Buyout amounts are high right now, but there are many other factors to consider when guiding employees to the right choice.
When searching for the right plan, it is important that retirees assume their health will one day change.
To build their wealth, retirement savers are advised to take advantage of tax-advantaged plans including 401(k)s and IRAs.
If they fear a sharp downturn, seniors may want to avoid locking up their retirement accounts in long-term bonds.
Clients adding investments other than target-date funds to their 401(k) or 403(b) could potentially hurt their bottom line.
These employees will need bigger savings than other age groups to fund a longer retirement horizon, according to a study.
Withdrawals for non-medical expenses would no longer be penalty-free under the proposal.
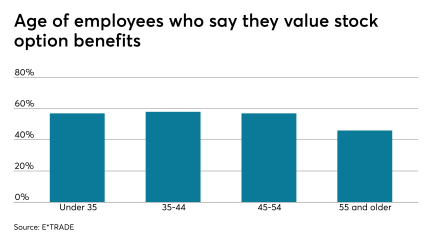
Workers, 35 and under, view stock plan benefits differently than older generations, and want greater participation in companies’ growth potential.
Before saving for retirement, young employees are advised to pay down high-interest debts and build an emergency fund, an expert says.
With steep competition for talent, it’s important clients think outside the conventional benefits packages to help their workforce build retirement savings.
With steep competition for talent, it’s important to think outside the conventional benefits packages to help your workforce build retirement savings.
Target-date funds can help risk-averse young workers ease into investing.
Some seniors are missing out on a potential 20% tax deduction, and “no one is talking about what a wonderful retirement planning technique" it is, says an expert.

Seniors in this position may face a tax bill and possibly a penalty if they dip into their 401(k) prematurely, says an expert.
A market correction only becomes a real risk if investors act and make buy or sell decisions to alleviate mental anguish today at the expense of tomorrow, says an expert.

Even if employers’ concerns are exaggerated, fear of fiduciary responsibility keeps them from offering lifetime income products.
Facing a difficult math problem of planning for retirement, advocates are exploring a path to lifetime income without traditional annuities.
Grandparents are advised to give cash gifts without putting their future financial security at risk.