The problem with the 4% retirement income rule
While there are strategies to help reduce risk, clients should recognize the order of investment returns is crucially important, an expert writes.
Follow Us
© 2026 Arizent. All rights reserved.

While there are strategies to help reduce risk, clients should recognize the order of investment returns is crucially important, an expert writes.
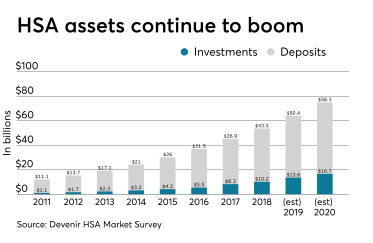
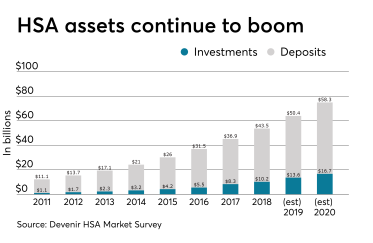
The new addition aims to help employees with healthcare expenses now and in retirement.
Many pre-retirees leave the workforce sooner than anticipated as a result of various factors, such as job loss and illness.
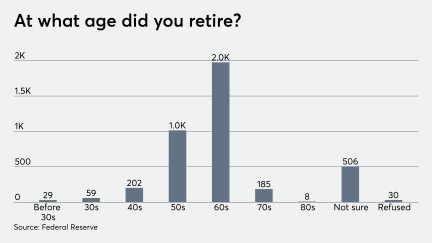
Within 10 years, millions of baby boomers will be facing financial and health-related challenges in retirement.
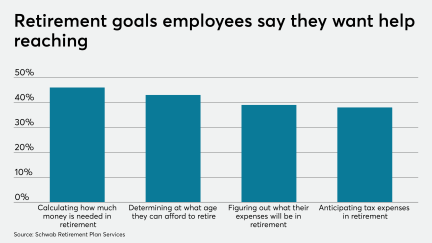
Investors who plan to retire early are advised to start saving as soon as possible and diversify their earnings with multiple sources of income.
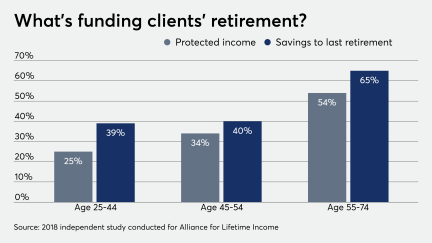
A recent study found American workers would face better retirement prospects if the federal government adopts certain public policy changes.
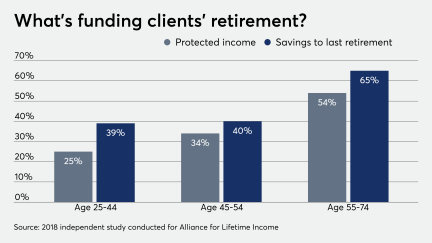
“The advice I give is to calculate the financial impact for each option,” an expert says.
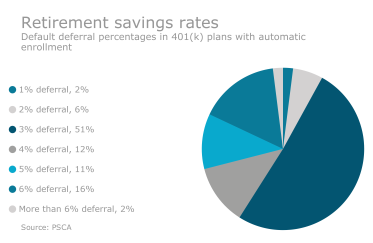
Research shows that both a match and automatic enrollment have significant positive effects, especially on groups that tend to have lower participation and contribution rates.
This rise of the so-called grey divorce has created a number of uncommon and complex issues for retirement accounts.
It is important for entrepreneurs to have an exit strategy and to take control of their debt.
Ill-prepared investors are advised to vigorously plan their expenses and aggressively save in their 401(k)s and IRAs.
The accounts will be managed through Wealthscape, allowing advisers access to their client’s finances to help manage rising healthcare costs.
Financially stressed workers hurt companies through higher healthcare costs and lost productivity. Programs to help them are not just an option for employers, but a business imperative.
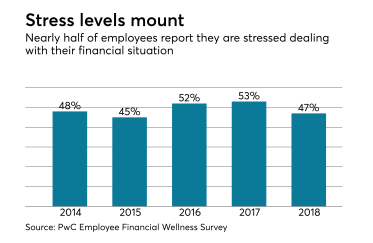
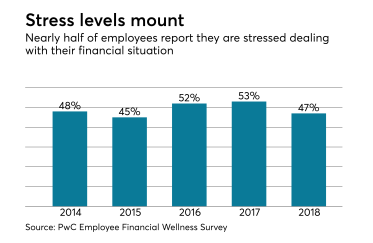
Financially stressed workers hurt companies through higher healthcare costs and lost productivity. Programs to help them are not just an option for clients, but a business imperative.
Deciding against auto-enrolling employees in retirement plans is a big miss benefit managers keep making.
Deciding against auto-enrolling employees in retirement plans is a big miss benefit managers keep making.
“By and large, many simply have not yet saved enough to retire comfortably.”
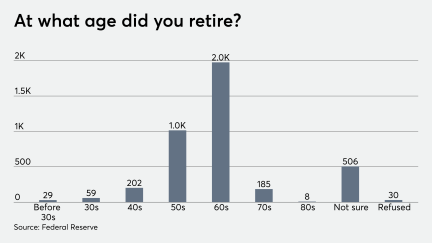
Financial planners should at least consider modeling early retirement to prepare clients for the possibility of uncertainty, says Morningstar.
Contributing to these accounts makes sense for clients who anticipate higher tax rates in the future.
This recently passed bill is groundbreaking retirement legislation and will substantially alter the landscape for employer-sponsored retirement plans and individual savers.