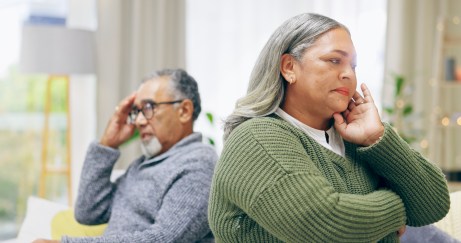
Gray divorce can derail retirement
Late-in-life divorces have more than doubled since 1990, and they often decimate retirement savings.
Follow Us
© 2026 Arizent. All rights reserved.

Late-in-life divorces have more than doubled since 1990, and they often decimate retirement savings.
This rise of the so-called grey divorce has created a number of uncommon and complex issues for retirement accounts.
For many workers, moving assets from old 401(k)s into a traditional IRA may not be a smart move. One reason: IRAs often don’t offer stable value or guaranteed fund investment options as do most 401(k)s.

Companies should consider offering older workers the option of taking a phased retirement to enable them to transition to the golden years.
Workers should consider contributing enough to their 401(k) plans to get their employer's match before making contributions to an IRA.
There are hundreds of rules and claiming strategies – the wrong one can have major repercussions.
Divorce is expected to be different for couples who are in their advance years than when they were younger.
A study by Merrill Lynch and Age Wave has found that 42% of women are concerned that they will outlive their nest egg when they reach the age of 80.

Even if an employee does not use the triple-tax-advantage of these accounts, the benefits are still valuable.
Employees aged 50 and above would no longer be able to make catch-up contributions on a pretax basis to their retirement plans under the Senate version of the GOP tax proposal.
Employees aged 50 and above would no longer be able to make catch-up contributions on a pretax basis to their retirement plans under the Senate version of the GOP tax proposal.