Retirement accounts at ‘serious risk’ as COVID-19 spurs bankruptcies
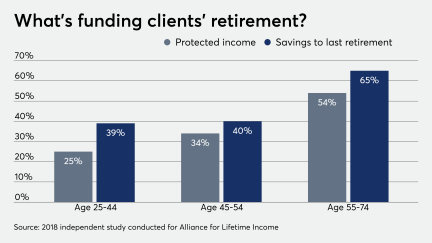
To protect client nest eggs, advisors must know which savings vehicles are protected — and they’re not all created equal.
Follow Us
© 2026 Arizent. All rights reserved.

To protect client nest eggs, advisors must know which savings vehicles are protected — and they’re not all created equal.
A recent study found American workers would face better retirement prospects if the federal government adopts certain public policy changes.
It is important for entrepreneurs to have an exit strategy and to take control of their debt.
Congress is considering a proposal that would allow small companies to create a multiple-employer retirement plan to enable their workers to build their nest eggs,
We have multiple goals in life and should be able to handle short-term debts and long-term goals without sacrificing one for the other, says one expert.
Short-term returns are mostly noise, which, by definition, largely cancels itself out over time
Short-term returns are mostly noise, which, by definition, largely cancels itself out over time
A new survey finds that three-quarters of baby boomers expect to postpone retirement due to a unrealistic expectations of medical expenses, among other reasons.
A new survey finds that three-quarters of baby boomers expect to postpone retirement due to a unrealistic expectations of medical expenses, among other reasons.
Workers with a high-deductible health plan will be better off setting up a health savings account, which offers tax benefits for savings earmarked for future medical expenses.
The proposed budget includes a provision that would give Medicare recipients the option to contribute to a health savings account, which would offer various tax benefits.
Far too many financial advisors overlook home equity as part of a retirement income plan.
The total out-of-pocket health care expenses of a 65-year-old couple in retirement could exceed $320,000, plus 5% annual increases.
The total out-of-pocket health care expenses of a 65-year-old couple in retirement could exceed $320,000, plus 5% annual increases.
Workers should be especially mindful of market movements during the "fragile decade," the span beginning five years before retirement until five years after retirement.
Clients should be especially mindful of market movements during the "fragile decade," the span beginning five years before retirement until five years after retirement.

Here’s how to decide whether your client should select the traditional or Roth IRA to put away for retirement and boost their savings.

Despite a stock market rally, it is possible that American's 401(k) returns will remain low.