Young adults can find retirement success. Here’s how
To start, these clients are advised to start saving as early and contribute enough to their 401(k)s to qualify for their employer's matching contribution.
Follow Us
© 2026 Arizent. All rights reserved.

To start, these clients are advised to start saving as early and contribute enough to their 401(k)s to qualify for their employer's matching contribution.
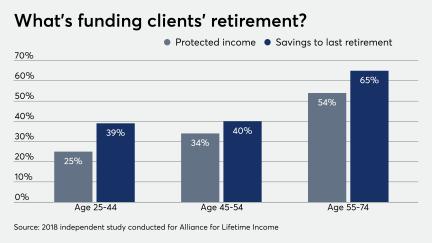
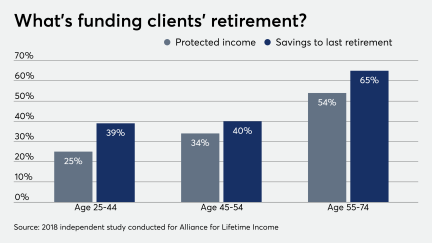
“It is really as important for plans to get people thinking about income rather than just accumulation,” an expert says.
Older clients who have lost a job prior to retirement are advised to first consider filing for unemployment insurance and begin making revisions to their budget.
Aside from income taxes, retirees will also pay consumer taxes and may face a 3.8% Medicare surtax.
The spike in the number of older employees in the workplace reflects a trend over the past decade.
Pre-retirees may consider funding a Roth account to take advantage of tax-free compounding and tax-exempt withdrawals in retirement, an expert writes.
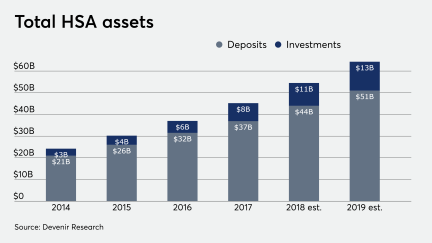
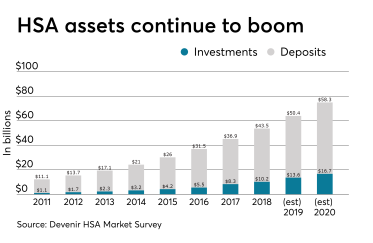
The HSA has become increasingly valuable for future medical expenses, "and the triple tax benefit simply can’t be ignored,” an expert says.
Pre-retirees are encouraged to save aggressively and create a list of things they plan to spend their money on without remorse, an expert says.
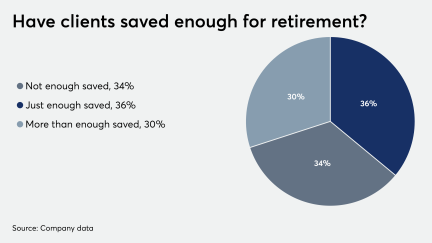
While it’s recommended they have at least three sources when they retire, just 6.8% of savers have done so, according to a report.
This rise of the so-called grey divorce has created a number of uncommon and complex issues for retirement accounts.
Ill-prepared investors are advised to vigorously plan their expenses and aggressively save in their 401(k)s and IRAs.
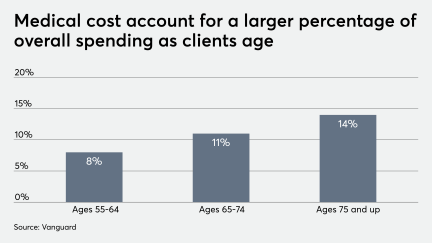
The accounts will be managed through Wealthscape, allowing advisers access to their client’s finances to help manage rising healthcare costs.
Contributing to these accounts makes sense for clients who anticipate higher tax rates in the future.
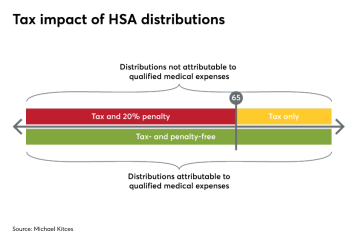
They are triple-tax advantaged, but also introduce significant challenges — especially for life partners with multiple accounts.
While seasoned employees won’t have to fill out the forms, all employees should be aware of how their tax situation may be affected.

The gender gap is alive and well when it comes to career timeouts and savings often take the hit.
Buyout amounts are high right now, but there are many other factors to consider when guiding employees to the right choice.
Clients should think of the years as empty buckets and keep the amount of income into each bucket level per year.
Chances are high that one or both parents who have left the workforce ahead of their full retirement age are still working out of necessity.
Age discrimination, unpredictable life shocks and involuntary retirement casts serious doubt on the “work longer” thesis.