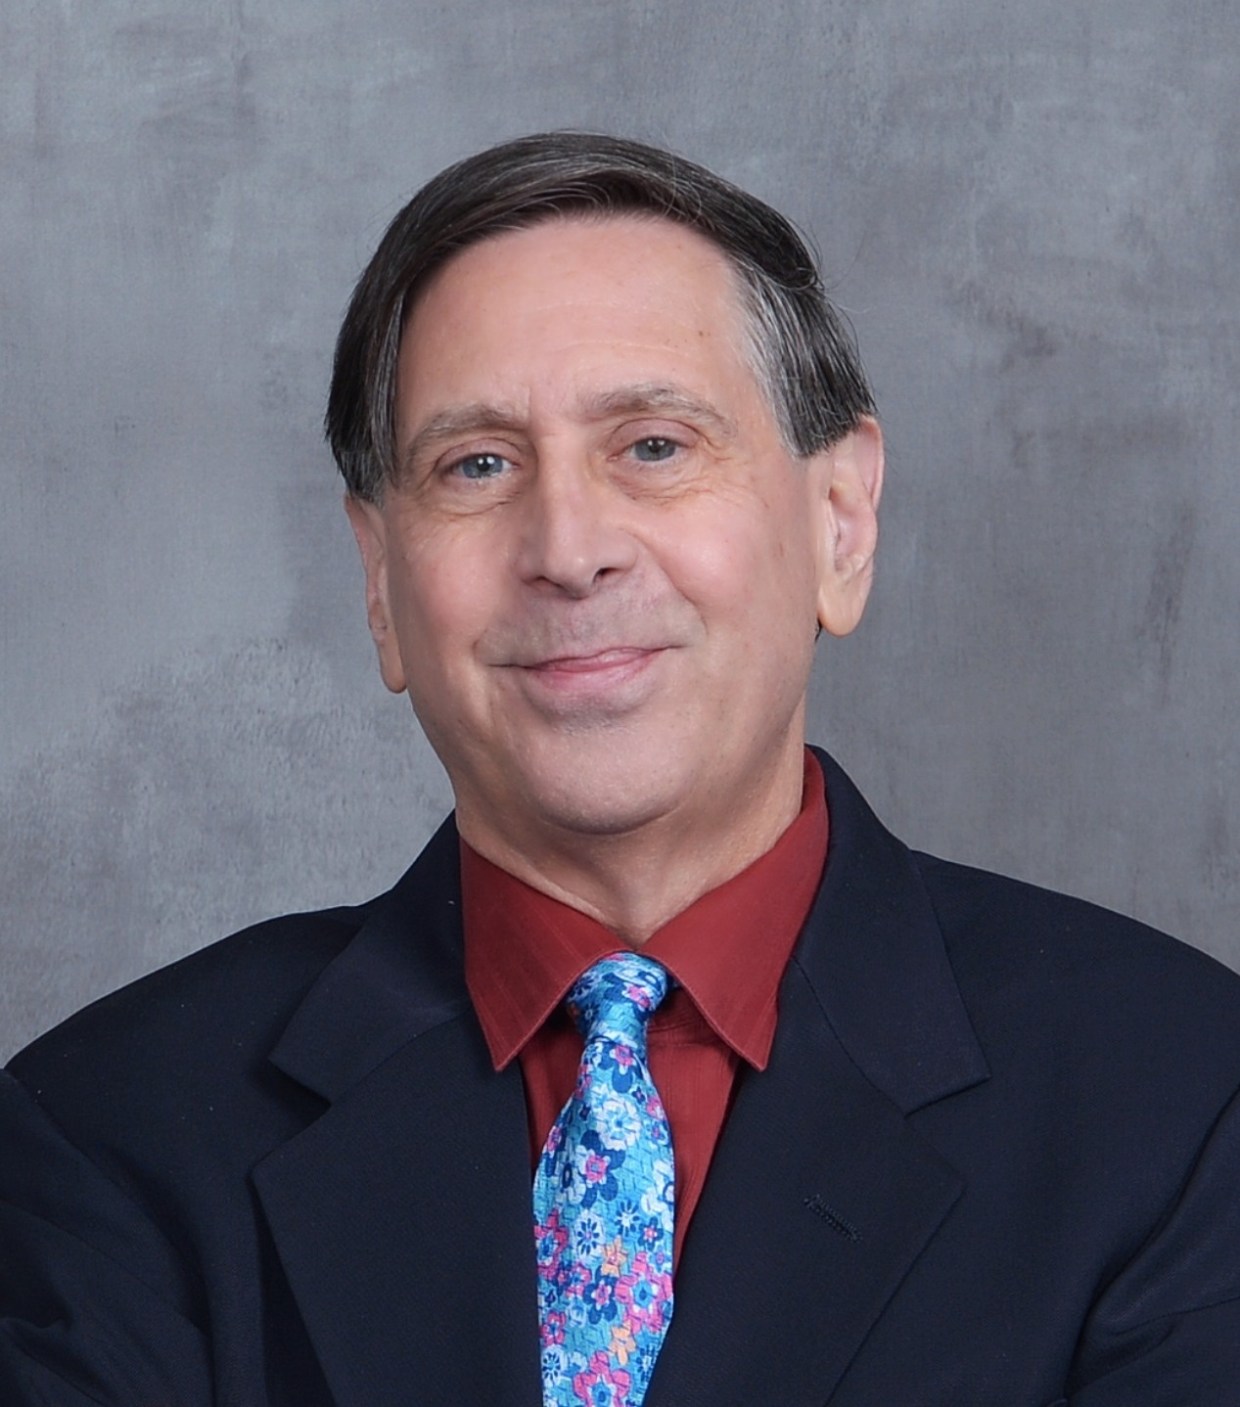
Welcome to Ask an Adviser, EBN’s weekly column in which benefit brokers and advisers answer (anonymous) queries sent in by our readers. Looking for some expert advice? Please submit questions to askanadviser@arizent.com. This week, we asked Ted Benna —whose “Father of the 401(k)” title dates back to when he created and gained IRS approval of the first 401(k) savings plan — to weigh in on the following:What are the pros and cons of pretax vs. after-tax Roth contributions?
Pretax savings enables someone to grow their retirement savings 15-50% faster than after-tax savings. Growing savings more rapidly is probably more important than what tax rates will be 20 or 30 years from now. A larger nest egg is a big plus if an event happens when someone is in their 50s, requiring them to dip into savings earlier than expected. That event could be a lost job, divorce, disability — or pandemic. This is true whether the savings involve employer-based plans such as a 401(k) or individual IRAs.