5 ways HSAs can help employees save for retirement

Published Updated 1 Min Read

With open enrollment in full swing, it’s time for your employees to review their health insurance options. Many workers will check the same box as last year, leaving their health insurance unchanged for another 12 months. But by making this quick, uninformed decision, employees are potentially missing out on a powerful retirement savings tool.

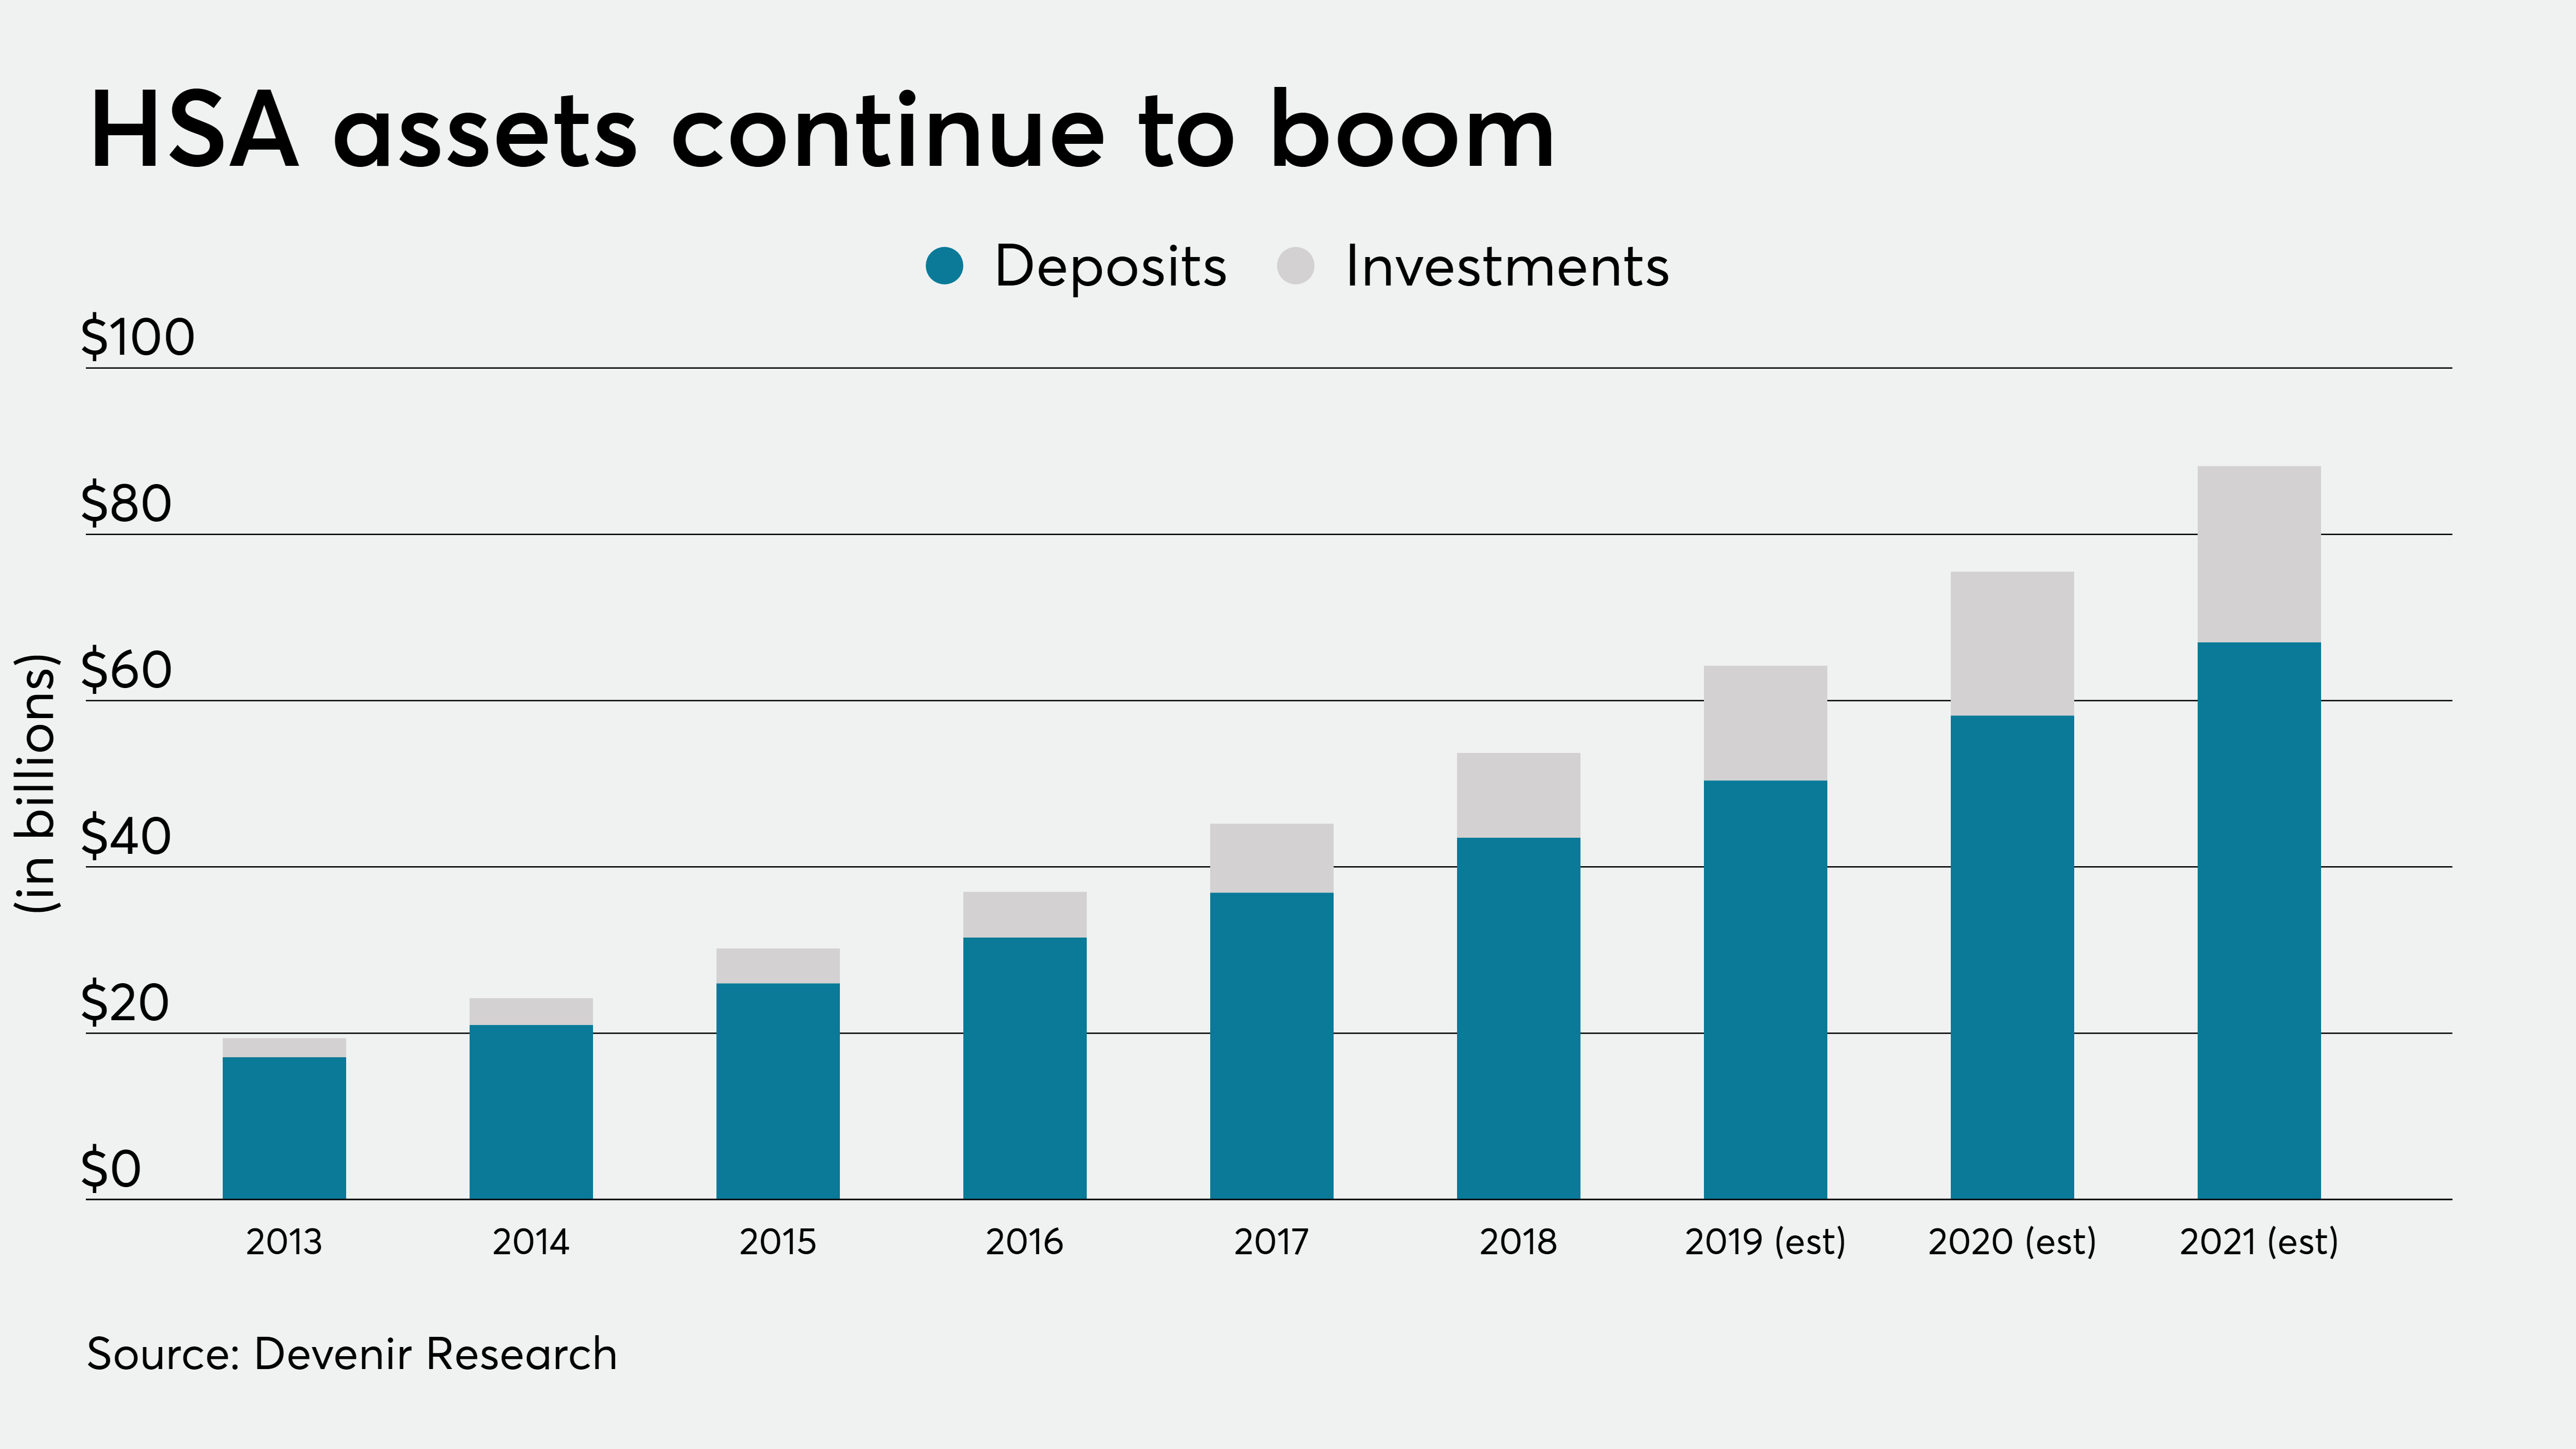
Health savings accounts are one way employees can save for retirement because they offer a tax-advantaged way to set aside money for qualified medical expenses. They’re also a great way to invest alongside other retirement accounts. With HSA contribution limits jumping to $3,550 for individuals and $7,100 for families in 2020, now is the time to consider their many benefits.
Unlike a flexible spending account, deposits into an HSA don’t have to be withdrawn and used by the end of the year. The use-it or lose-it rules do not apply. Employees can invest and grow the money in their HSA just as they would a 401(k). If you don’t incur a lot of out-of-pocket healthcare expenses throughout the year, contributions can potentially grow for decades into the future. This helps employees plan for a significant, long-term expense that often gets overlooked when thinking about retirement.

With three separate tax advantages, HSAs offer the greatest potential for tax savings compared to 401(k)s, Roth IRAs and just about every retirement savings option.

Anthony Carlton
Financial planner

Anthony Carlton is a financial planner for LearnLux who works virtually with clients located all over the U.S.


For reprint and licensing requests for this article, click here.


More From Employee Benefit News

Sign Up Form

Login Modal Form