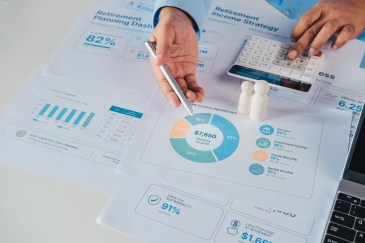
The incorporation of guaranteed minimum withdrawal benefits (GWMBs) into defined contribution plans may reduce the level of assets required for plan participants to achieve the same level of retirement income, according to Prudential Retirement.
In a white paper titled “What Employers Lose in the Shift: From Defined Benefit to Defined Contribution Plans … And How to Get it Back,” Prudential says that by pooling the longevity risk of defined contribution participants in annuities with GMWBs, not only do investors receive income for life but more income from the same amount of savings.