Two House bills target workplace retirement plans
The legislation aims to improve security with increased access to lifetime income and simplify plan procedures for plan sponsors.
Follow Us
© 2026 Arizent. All rights reserved.

The legislation aims to improve security with increased access to lifetime income and simplify plan procedures for plan sponsors.
Charles Schwab senior multi-asset class strategist Jake Gilliam sounds off on TDF choices and how plan sponsors can pick the right funds for employees.
The benefits update is part of a $250 million investment initiative in the wake of the new tax reform bill.
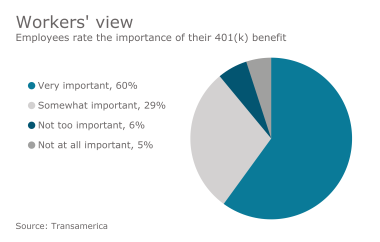
Plan sponsors should refocus the end-of-work conversation by providing employees education and access to lifetime income products, says TIAA managing director David Ray.

The legislation aims to improve security with increased access to lifetime income and simplify plan procedures for plan sponsors.
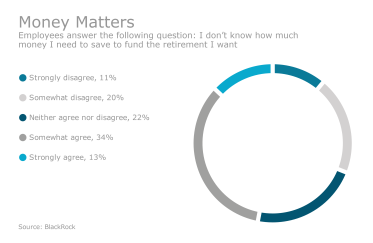
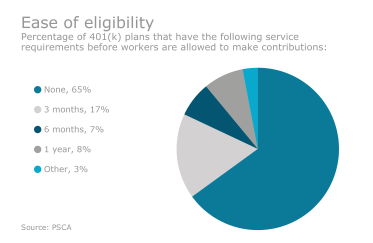
Advisers should help employers to reduce eligibility times and consider using gamification to communicate the benefit.
The benefits update is part of a $250 million investment initiative in the wake of the new tax reform bill.
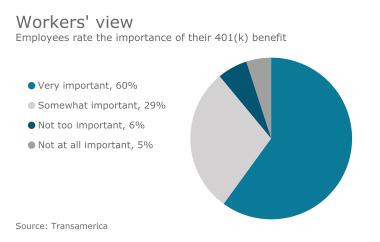
Retirees should stick to their strategies and diversify their portfolios with various sources of income.
Employers should make enrollment automatic and easy, reduce eligibility times and consider using gamification to communicate the benefit.
Employees should do a quick assessment of their retirement prospects while still working.

U.S. financial firms plan to expand a secretive project protecting bank accounts against crippling cyber attacks so that it will also guard trillions of dollars in investment funds.

Many employees with access to Roth IRAs or designated Roth accounts in their 401(k), 403(b) or 457 savings plans are not taking advantage of them.
One strategy to enhance financial prospects is to get a part-time job via the gig economy.
Understanding participant needs means having the courage to directly ask what topics are the most pressing, and then address them.
Many younger workers find it difficult to think beyond their student debt, which averages $32,731 with an average monthly payment of $393, according to the Federal Reserve.
Plan participants should review a full market cycle, index efficient asset classes and eliminate closet indexers.
Understanding participant needs means having the courage to directly ask what topics are the most pressing, and then address them.
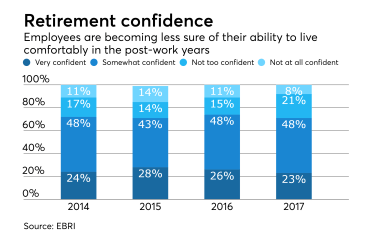
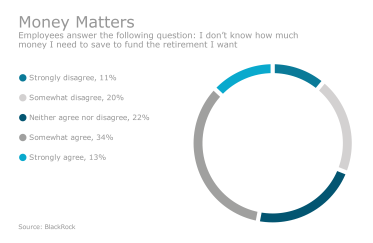
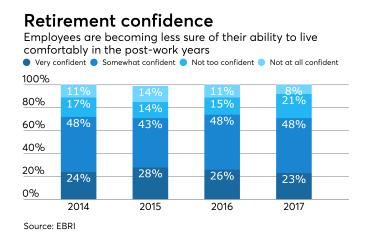
Money worries continue to plague employees but executives struggle to create plans that address workers’ fiscal woes.
Those who leave the workforce and are sitting on losing investments may do tax-loss harvesting, or they may donate their winning holdings to a charity to avoid the capital gains tax
Money worries continue to plague employees but executives struggle to create plans that address workers’ fiscal woes.