With little saved, employers and aging employees share same fear: Can retirement happen?
As nearly one in three workers consider putting off retirement, companies must plan for different generations working together efficiently.
Follow Us
© 2026 Arizent. All rights reserved.

As nearly one in three workers consider putting off retirement, companies must plan for different generations working together efficiently.
Plan sponsors can help female employees save more for their post-work years by encouraging and facilitating 401(k) account consolidation.
Although the cost of living adjustment increased 2% this year, half of retirees cannot expect a substantial increase in their benefits.
The majority of workers say they have enough saved for their post-work years, thanks to a workplace plan, but they aren’t considering healthcare expenses or big debts. Here’s what employers can do.
Plan sponsors can help female employees save more for their post-work years by encouraging and facilitating 401(k) account consolidation.
Two in three plans offer a Roth savings feature, an option 401(k) participants should take advantage to reduce their tax liability.
The majority of workers say they have enough saved for their post-work years, thanks to a workplace plan, but they aren’t considering healthcare expenses or big debts. Here’s what employers can do.
Employers should inform their workers about the benefits of increasing their 401(k) contributions and investing in health savings accounts, among other tips.
Despite the bumpy ride for 401(k) plans in the first half of this year, some analysts say investors can expect a better scenario for the remainder of 2018.
More retirement investors are including cryptocurrency in their portfolio because it helps them achieve diversification.
Cash balance, deferred compensation and profit-sharing plans are gaining in popularity — especially for small employers.

When planning for retirement, it is important for workers to think in terms of their source of income in retirement, but which retirement vehicle offers the best perk?
While many retirees have prepped well for whatever the economy and markets may bring, far too many others have not, an expert says.
Automatic enrollment is starting to generate a backlash with many critiques from analysts saying workers may run up debt to make up for the reduced take-home pay
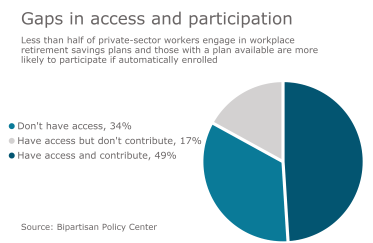
Cash balance, deferred compensation and profit-sharing plans are gaining in popularity – especially for small employers.

Retirees have median savings of $839,000, but many of them are unwilling to spend away their nest egg.
While these services are far from perfect, they are a useful way to start a conversation with employees planning for their post-work years.
While these services are far from perfect, they are a useful way to start a conversation with employees planning for their post-work years.
Benefit advisers have a definite role in helping employers take steps toward building a more financially-secure workforce.
Starting small, with financial checklists and cash flow worksheets, can have a large impact on plan participants.