Employers advised to re-evaluate retirement plan costs
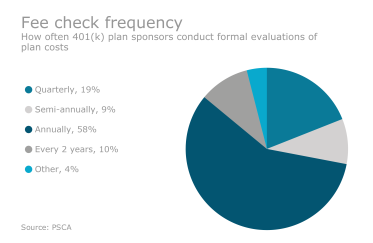
Even with disclosure rules in place, it is sometimes hard for plan sponsors to discern the fairness of the fee structures in their retirement plans.
Follow Us
© 2026 Arizent. All rights reserved.

Even with disclosure rules in place, it is sometimes hard for plan sponsors to discern the fairness of the fee structures in their retirement plans.
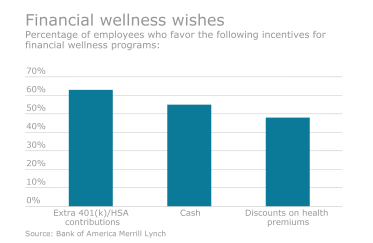
To improve employees’ long-term finances, encourage plan sponsors to look past typical 401(k) metrics and concentrate on a comprehensive approach to financial services.
To help improve employees’ financial prospects post-work, plan sponsors should look beyond the typical metrics of 401(k) contribution and participation rates and concentrate instead on a comprehensive financial wellness approach.
The DOL’s April 2017 deadline means employers should start familiarizing themselves now with their responsibilities under the new regulations.
The DOL’s April 2017 deadline means employers should start familiarizing themselves now with their responsibilities under the new regulations.
Nearly half of U.S. workers have no retirement savings, so plan sponsors should embrace auto-enrollment and online education and advice, says adviser Robert Lawton.
Consumer prices may be relatively stable overall, but healthcare costs for people 65 and over are rising rapidly.
For workers looking at life post-career, steady income is more important than return on investment.
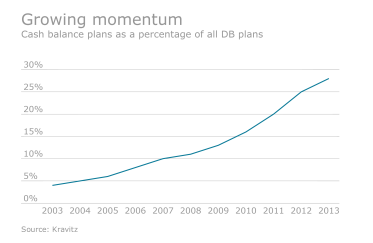
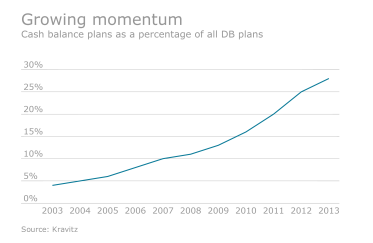
Employers looking to minimize DB program risks should consider market-return cash balance plans, according to October Three Consulting’s Larry Sher.
DC plan sponsors should be thinking about where they are going to find alpha, says BlackRock's Anne Ackerley.
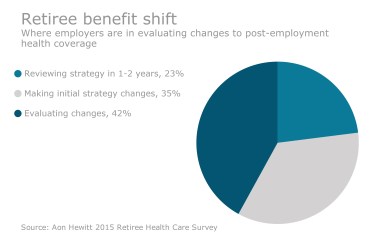
Traditional group coverage is dropping as employers help workers find other options, including private exchanges.

Employers looking to minimize DB program risks should consider market-return cash balance plans, according to October Three Consulting’s Larry Sher.
Some group programs are being dropped and workers being moved to individual private exchanges.
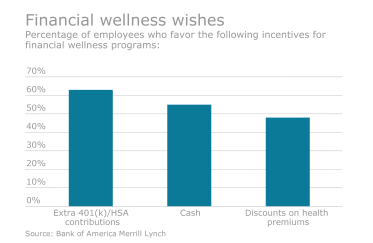
Nearly half of large employers offer some type of program, yet only about a third of workers say they have access to one, highlighting a key disconnect about well-being efforts.
In a more volatile market, DC plan sponsors should be thinking about where they are going to find alpha, says Anne Ackerley, managing director of BlackRock.
The 3% deferral rate in nearly half of auto-enrolled plans is simply too low, says State Street Global Advisors’ Melissa Kahn.
Three strategies to consider when helping employers structure workplace programs that offer employees financial tools for their future.
Public policies to boost participation in DC plans are critical but so is getting participants to save more, says Melissa Kahn.
Nearly half of large companies offer some type of program, yet just over one-third of workers say they have access to one, highlighting a disconnect between available benefits and employees’ understanding of them.
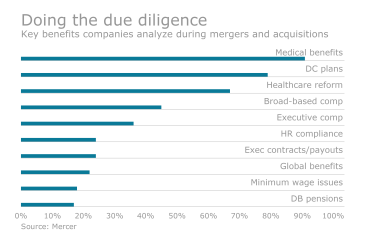
Helping clients understand the pension and benefit plans of seller organizations is an important part of any acquisition.