
Retirement income strategies for next bear market
Clients should be especially mindful of market movements during the "fragile decade," the span beginning five years before retirement until five years after retirement.
Follow Us
© 2026 Arizent. All rights reserved.

Clients should be especially mindful of market movements during the "fragile decade," the span beginning five years before retirement until five years after retirement.
The most important consideration is that employees are able to complete the 35-year work period because benefits are based on the 35 highest-paid years from their careers.
Clients should plan to replace roughly 80% of their pre-retirement income after they leave the workforce for good.
Make sure workers understand that a 401(k) rollover could trigger a hefty tax bill, and that liquidating assets before the age of 59 1/2 could mean a hefty penalty.
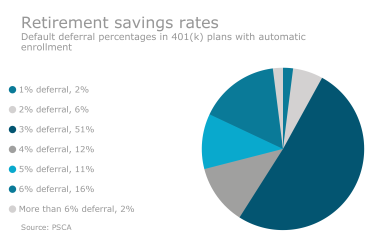
Make sure clients understand that a 401(k) rollover could trigger a hefty tax bill, and that liquidating assets before the age of 59 1/2 could mean a hefty penalty.
Clients should work together with their spouses and plan as a couple to develop a Social Security claiming strategy that will maximize their retirement benefits.
Seniors are advised to withdraw from taxable and other retirement accounts before taking distributions from their HSA.
The government should tax the health insurance that employers provide to employees to generate revenue to fix Social Security's financial woes, says Harvard professor.
Employers' 401(k) matching contributions this year are likely to reach 4.7% of worker's pay, up from 3% in 2009.
Employers' 401(k) matching contributions this year are likely to reach 4.7% of worker's pay, up from 3% in 2009.
To avoid paying high fees, retirement savers should ensure that their plan administrator is a no-load fund company and avoid overpriced house funds.
Retirement investors can use their loss carryforward to write off the taxes triggered by a Roth IRA conversion.
Although the market continues to rally, a possible setback remains likely and retirement investors should be ready for this scenario.
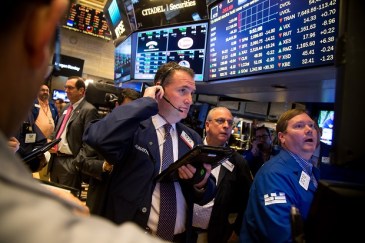
Although the market continues to rally, a possible setback remains likely and retirement investors should be ready for this scenario.
Employers should be encouraged to provide their workers affordable, simplified long-term care insurance for employees age 45 and older, says report from the Bipartisan Policy Center.
Retirees are better off taking withdrawals from their retirement accounts in their 60s so they spread out their tax liability.
Those who leave the workforce are better off taking withdrawals from their accounts in their 60s so they spread out their tax liability.
Seniors who want to relocate in retirement to a different place from what their spouse prefers may opt to maintain two homes.
Although traditional IRAs offer upfront tax deductions, clients will have to pay taxes later in life when they likely will be in a higher tax bracket.
Although traditional IRAs offer upfront tax deductions, clients will have to pay taxes later in life when they likely will be in a higher tax bracket.