3 smart money moves for workers in their 40s
One important somber step for 40-something clients is to consider what happens to their assets when they die.
Follow Us
© 2026 Arizent. All rights reserved.

One important somber step for 40-something clients is to consider what happens to their assets when they die.
After establishing an automatic enrollment program, employers should implement new features to fine-tune employee retirement savings plans.
After establishing an automatic enrollment program, employers should implement new features to fine-tune employee retirement savings plans.
Chris Christie, a Republican with less than 11 months left as New Jersey’s governor, must find a way to balance his final state spending plan after cutting taxes, pledging a higher pension contribution and disclosing a revenue shortfall.
‘Obsolete and overly restrictive limitations’ are holding back pension plan design, says Principal’s Mike Clark.
Congress is pushing back against post-work savings programs as states like California, Washington and Oregon begin their initiatives.
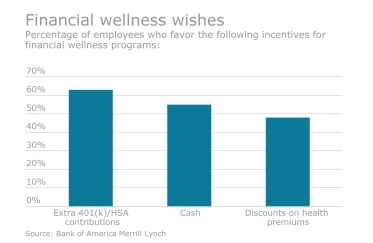
Employees with a low self-rating of financial knowledge are less likely to engage with the tools and resources employers put in front of them.
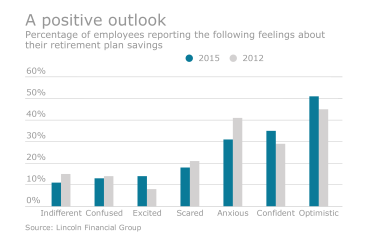
Employees aren’t saving enough for retirement. But employers can help by offering auto-enrollment and auto-escalation.
Focusing on sponsor control, governance and design features will lead advisers and clients to innovation.
Two-thirds of all Americans don’t contribute anything to a 401(k) or other retirement account available through their employer.
Congress is pushing back against post-work savings programs as states like California, Washington and Oregon begin their initiatives.
‘Obsolete and overly restrictive limitations’ are holding back pension plan design, says Principal’s Mike Clark.
Let’s enact a uniform fiduciary standard so all clients are protected and any appearance of compensation bias is removed, urges John Ludwig.
Plan sponsors should always respond to employee inquiries in a timely way and correctly file Form 5500, says retirement adviser Robert Lawton.
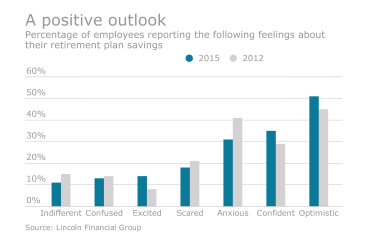
More employers are embracing the idea that a financially aware and secure employee is a happier, healthier and more productive individual.
Employees aren’t saving enough for retirement. But employers can help by offering auto-enrollment and auto-escalation.
The average plan balance rose to $92,500 at the end of the fourth quarter, Fidelity Investments reports.
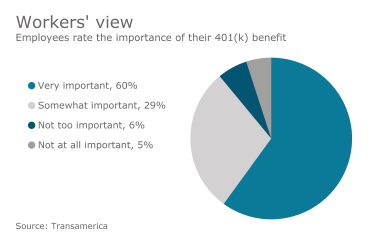
As benefit providers look to boost their employees’ fiscal well-being, they are often left with more questions.
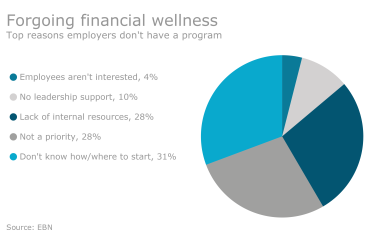
As benefit providers look to boost their employees’ fiscal well-being, they are often left with more questions.
Contractors and freelancers are not putting adequate planning into their post-work years.