Public pension doomsday clock stops as funds gain 15%
U.S. state and local governments have good reason to root for stocks to rebound from the crash.
Follow Us
© 2026 Arizent. All rights reserved.

U.S. state and local governments have good reason to root for stocks to rebound from the crash.
Nearly 60,000 workers and recent retirees of the health insurance giant will get a retirement plan boost.

Using lowest-cost share classes, performing an annual investment fund review and distributing required fee notices are among best practices.
Even if those assets are used to pay for nonmedical expenses, an HSA can still be ahead of a 401(k) plan or an IRA.

Employees have a hundred—if not a thousand—possible options to consider when claiming Social Security benefits.
Employers should build an education program, perform an objective review of investments and benchmark features.
Millennials don’t know how to manage stock market expectations, Gen X struggles with savings and baby boomers don’t realize the benefits they could gain from one or two extra years in the workforce.
Retirees who consider taking withdrawals from their 401(k) and other similar plans should account for the tax impact before making a decision.
Plan sponsors worry record keepers will follow suit, limiting the investment options employers are able to offer employees through their workplace 401(k) plans.
Savers are starting to take money out of their 401(k) accounts—despite taxes and penalties involved—assuming it will be replaced as markets continue to surge upward.
Plan sponsors worry record keepers will follow suit, limiting the investment options employers are able to offer employees through their workplace 401(k) plans.
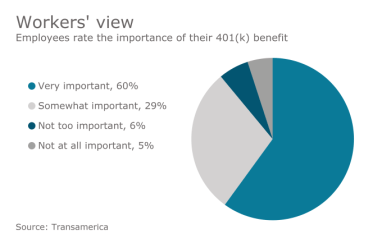
Collective Investment Trusts can have cost-saving advantages, are increasingly accessible and provide a long-term investment perspective.
More companies will stretch matching contributions, include HSA information in education sessions and incorporate behavioral economics/finance elements in plan design.
Lawmakers in Illinois are so desperate to shore up the state’s massively underfunded retirement system that they’re willing to entertain an eye-popping wager.
The Washington bank chain increased its retirement contribution to 8% following the tax reform bill.
About half of mid-sized and large companies plan to expand personal financial planning and increase retirement funds, according to a new Willis Towers Watson report.
Employees should consider that state laws may differ on who may be legally recognized as a beneficiary's spouse and thus whether their partner would be entitled to spousal benefits.
Build an education program, perform an objective review of investments and benchmark features are a few of the activities advisers should encourage now.
Using lowest-cost share classes, performing an annual investment fund review and distributing required fee notices are among best practices.
There have been some modest attempts in the past few years to shore up and fill in gaps in this country's haphazard system of retirement savings.