Fidelity to launch student loan repayment benefit for employers
The financial services firm’s new program will allow companies to make after-tax contributions toward their workers’ education debts.
Follow Us
© 2026 Arizent. All rights reserved.

The financial services firm’s new program will allow companies to make after-tax contributions toward their workers’ education debts.
When the current bull market fever subsides (or crashes), dividend investing will regain some of its lost appeal, writes an expert.
When the current bull market fever subsides (or crashes), dividend investing will regain some of its lost appeal, writes an expert.
According to WalletHub research, these cities top the list in affordability, quality of life and healthcare.
Retirement expert Ted Benna’s new guide features three models that could appeal to businesses looking to simplify the savings process.
Workers want personalized, on-demand guidance offered through digital channels, a new Betterment for Business survey finds.
According to WalletHub research, these places rank low in affordability, quality of life and healthcare.
A lack of widespread auto-portability in the present U.S. retirement system is causing many plan sponsors to pay plan cash-outs to terminated employees.
When it comes to establishing a robust retirement program, BP’s Cliff York relies on open communication, using current data to provide employees what they need to have success in their post-work years.

Each pre-retiree couple is in a unique circumstance, and needs to account for their health and longevity, as well as their willingness and ability to work.
A lack of widespread auto-portability in the present U.S. retirement system is causing many plan sponsors to pay plan cash-outs to terminated employees.
New data from United Benefit Advisors suggests that firms with fewer than 100 employees can compete for talent along with bigger companies.
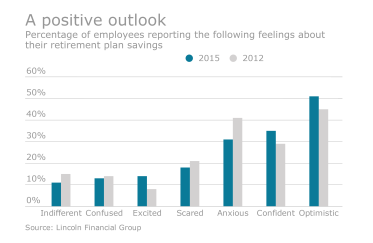
While an increasing number of these employers say retirement plans help them attract and retain talent, the majority says they don’t have the capabilities to set one up.
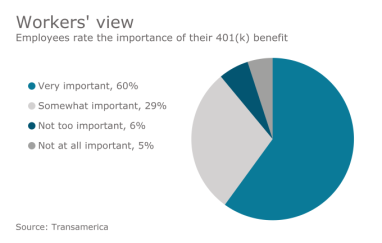
Staying in a plan’s qualified default investment alternative rebalances employee accounts and ensures age-appropriate allocations.
While an increasing number of these employers say retirement plans help them attract and retain talent, the majority says they don’t have the capabilities to set one up.
In a perfect world, the largest expenses in retirement would be for fun things like travel and entertainment. In the real world, retiree healthcare costs can take an unconscionably big bite out of savings.
Women are spending fewer years being married, new research finds, a change that “has significant implications for financial planning.”
With the goal of improved participant outcomes, a simplified approach using straightforward language could be more attractive to employees.
Participants don’t need a million choices to save successfully for retirement.
Plan sponsors must continue to offer automatic plan features and do a better job of vetting target-date funds.