401(k), IRA account balances rise to record levels
Employees continue to increase their contributions to retirement accounts, new Fidelity research finds.
Follow Us
© 2026 Arizent. All rights reserved.

Employees continue to increase their contributions to retirement accounts, new Fidelity research finds.
More employers will stretch matching contributions, include HSA information in education sessions and incorporate behavioral economics/finance elements in plan design.
In wake of tax reform, employers can encourage employees to invest in HSAs, build up their 401(k), pay off debt and build an emergency fund.
Employers play a big role in the savings success of lesbian, gay, bisexual or transgender employees because they are more likely to plan for and save for their post-work years if their firm sponsors a 401(k).
As long as their earnings won't exceed the limit set by the Social Security Administration, they will not lose their benefits.
Advisers must make the case that stable value funds are a good fit to include in defined contribution plans for risk-averse employees.
Employers play a big role in the savings success of lesbian, gay, bisexual or transgender employees because they are more likely to plan for and save for their post-work years if their firm sponsors a 401(k).
Plan sponsors should document meetings, put employee needs first and ensure they have a properly structured retirement plan committee.
Only less than one-third of workers polled by TIAA claimed that they are contributing to an IRA
Using lowest-cost share classes, performing an annual investment fund review and distributing required fee notices are among best practices.
The beauty conglomerate added the perk to better serve its millennial-oriented workforce.
Employers should build an education program, perform an objective review of investments and benchmark features.
The beauty conglomerate added the perk to better serve its millennial-oriented workforce.
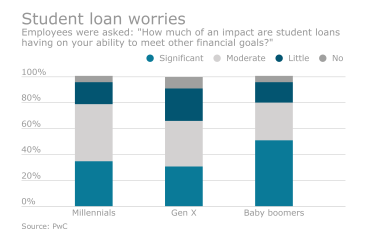
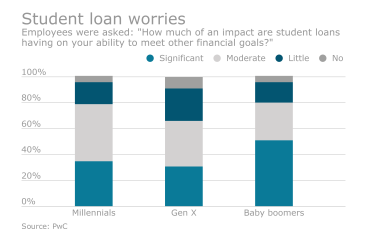
Millennials don’t know how to manage stock market expectations, Gen X struggles with savings and baby boomers don’t realize the benefits they could gain from one or two extra years in the workforce.
Plan sponsors worry record keepers will follow suit, limiting the investment options employers are able to offer employees through their workplace 401(k) plans.
Plan sponsors should end automatic cash-outs, offer roll-ins as part of a financial wellness program and engage all participants on crucial decision-making.
Plan sponsors worry record keepers will follow suit, limiting the investment options employers are able to offer employees through their workplace 401(k) plans.
Collective Investment Trusts can have cost-saving advantages, are increasingly accessible and provide a long-term investment perspective.
More companies will stretch matching contributions, include HSA information in education sessions and incorporate behavioral economics/finance elements in plan design.
The Washington bank chain increased its retirement contribution to 8% following the tax reform bill.