How one employer opened workers’ eyes to the benefits of HSAs
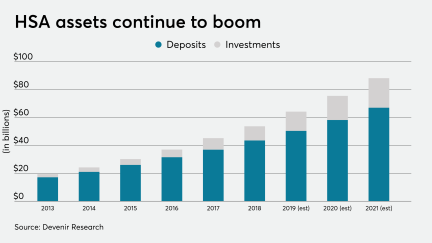
Investing in these tax-advantaged accounts can help improve employees’ overall well-being.
Follow Us
© 2026 Arizent. All rights reserved.

Investing in these tax-advantaged accounts can help improve employees’ overall well-being.
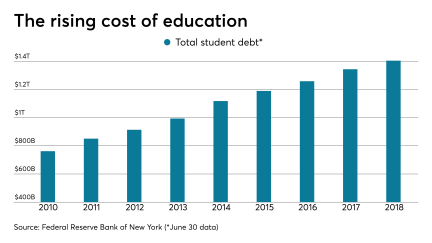
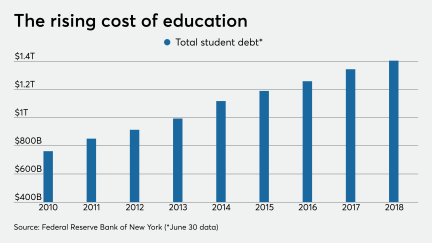
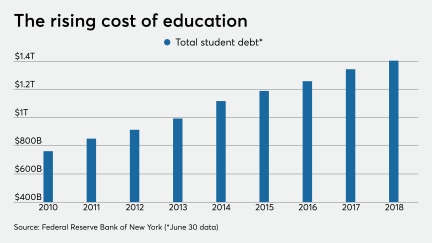
The number of employers offering student loan debt repayment programs has doubled since 2018.
Offering a range of perks can help clients meet the needs of employees at all life stages.
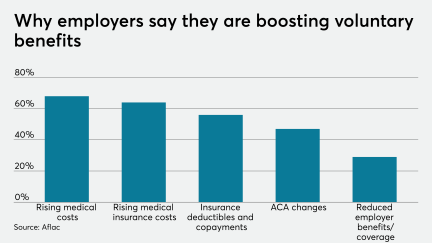
Workers often believe current debt prevents them from sparing any dollars for the future.
Offering a range of perks can help meet the needs of employees at all life stages.

Workers often believe current debt prevents them from sparing any dollars for the future.
The software company has been beefing up its financial wellness benefits echoing larger trends among employers nationwide.
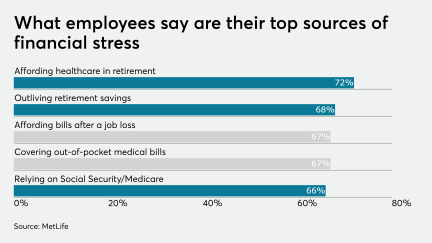
“If retention is an important factor for an employer, financial wellness is quite worth the investment,” one benefits consultant says.
A first-in-the-nation bill that drew unanimous support from the state Senate failed to get over the finish line this year. What happened?
The company will help its nearly 10,000 team members get paid early, organize and budget their money.

While traditional coverage package remains relevant, a new generation requires new offerings.
A proposed rule hopes to remove barriers and encourage the creation of multiple employer retirement plans.
While traditional coverage package remains relevant, a new generation requires new offerings.
The investment bank is hoping the tool will give employees the resources they need to be smarter with money.
Despite auto portability’s proven ability to cut 401(k) withdraws, a solution addressing leakage and the lack of seamless plan-to-plan asset mobility is missing.
The employer is offering workers up to $6,000 to help pay down their college debt.
The investment bank is hoping the tool will give employees the resources they need to be smarter with money.
Despite auto portability’s proven ability to cut 401(k) withdraws, a solution addressing leakage and the lack of seamless plan-to-plan asset mobility is missing.
If they fear a sharp downturn, seniors may want to avoid locking up their retirement accounts in long-term bonds.
Benefit advisers might consider looking in these markets to beef up financial wellness product sales.
